FRANKFURT AS A FINANCIAL CENTER & FINANCIAL CENTER GERMANY: “What must a family office be able to understand, coordinate, and evaluate in order to provide professional, long-term management of family wealth?” (INTERVIEW – Dr. Sigrid Mulas, Managing Director of Fürstenberg’s Specialized Seminars)

Family office topics have significantly expanded in scope in recent years. In addition to traditional investment issues, governance, succession, corporate investments, international structures, and the professional coordination of various experts are taking center stage. In the run-up to the Family Office 2026 Annual Conference, Markus Hill of Finanzplatz Frankfurt am Main spoke with Dr. Sigrid Mulas, Managing Director of Fürstenberg’s Specialized Seminars, about the event’s further development, the redesign of the “Certified Family Officer (FvF)” program, and the question of what skills family officers need today. Of particular interest was the focus on the intersections: Family office work is not limited to individual disciplines. Rather, what matters most is how legal, tax, financial, family, and governance issues are integrated in practice. The conversation also provided insights into the key topics of the 2026 annual conference in Bad Neuenahr, as well as the development of a professional and networking environment surrounding the Certified Family Officer training program.

Hill: Dr. Mulas, the 2026 Family Office Annual Conference is set to undergo some changes. What’s new?
Mulas: We are clearly evolving the 2026 Annual Conference. For one thing, after five years, it will take place in Bad Neuenahr this year. For another, Dr. Florian Oppel will take over as conference chair alongside Dr. Henning Schröer. This also allows us to set a new tone in terms of content. The annual conference is intended to become even more of a forum where current family office issues are not only presented but also analyzed from a professional perspective and openly discussed.
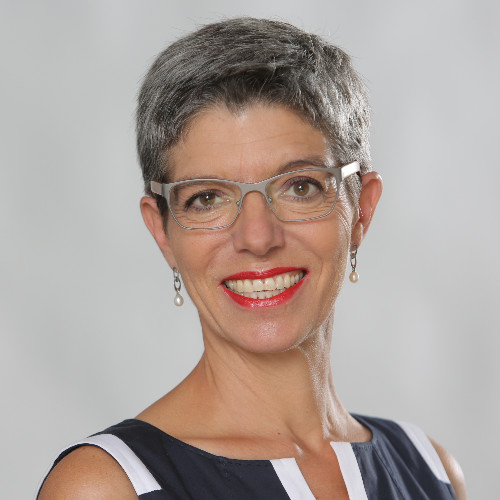
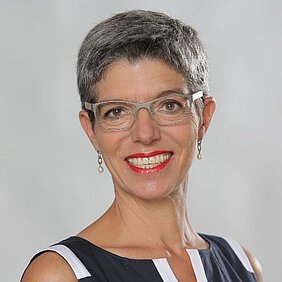
Dr. Sigrid Mulas, Geschäftsführerin der Fachseminare von Fürstenberg


Hill: What sets your annual conference apart from traditional wealth management, private banking, or investment conferences?
Mulas: Many events in this field view family offices primarily as investors or a target audience for products. That’s too narrow for us. Our focus is on the overall architecture of complex family wealth: family, business, assets, governance, succession, risk, legal matters, taxes, and investments. Investment topics play a role, but not in isolation. The key question is: What must a family office be able to understand, coordinate, and assess in order to provide professional, long-term stewardship of family wealth?

Hill: Can you tell us anything yet about the 2026 program?
Mulas: Yes, the program has now been published and clearly illustrates the direction in which the annual conference is evolving. We begin with the question of how family wealth can be strategically safeguarded in times of crisis, and then cover succession and structural measures, real estate, strategic asset allocation, private debt, and minority stakes in family businesses. On the second day, the focus will be more on operational and governance-related issues: AI in the family office, family office governance, the advisory board, as well as communication and reputation management for entrepreneurial families. In this way, the conference covers exactly the breadth of topics that modern family office work demands today: wealth, family, business, governance, investments, and risk must all be considered together.


Hill: Are there any program highlights you’d particularly like to draw attention to?
Mulas: All the presentations promise exciting insights because they offer different perspectives on the day-to-day operations of professional family offices. However, two topics may be of particular interest to your readers: first, strategic asset allocation for entrepreneurs and entrepreneurial families, because here, investment is viewed not in abstract terms but through the lens of the principals’ thinking and decision-making logic. Second, private debt, as this asset class is becoming increasingly relevant for family offices and other professional investors and requires a disciplined assessment of returns, risk, segments, and selection criteria. Additionally, the presentation on minority investments in family businesses is fascinating because it combines family equity, long-term partnerships, and governance issues. However, it’s important to note that the annual conference is not just a series of presentations. The exclusive alumni gathering of Certified Family Officers (FvF) and the group dinner provide a setting where these topics can be explored further in confidence.

Hill: “Networking” is a common promise in the professional development industry. In your view, when does this actually translate into professional value?
Mulas: When a network isn’t just open to anyone and is based on a shared professional foundation. That’s exactly the case with our graduates. They’ve completed the same program, share a basic understanding of professional family office work, and then reconnect at the annual conference or at regular get-togethers. This fosters not only connections but also trust—and trust is a true foundation for work in this field.

Hill: How large has this network grown?
Mulas: Since the program began in 2017, around 130 participants have earned the Certified Family Officer (FvF) designation. This isn’t a mass program, but rather a community that has grown organically. In 2026, we redesigned the program because the requirements for family officers have changed.

Hill: What was no longer sufficient about the previous program design?
Mulas: The demands placed on Family Officers have evolved significantly, and over the past nearly ten years, we’ve received a great deal of feedback and developed further expertise. In practice, it’s becoming even more evident today that professional family office work doesn’t fail due to a lack of specialized knowledge, but rather due to a lack of integration: law, taxes, assets, family, governance, and risk must be considered together. The topics of value creation and international context are of paramount importance. That is why we have fundamentally redesigned the 2026 program—based on numerous previous programs, participant feedback, and evolving professional perspectives. The goal is no longer the accumulation of knowledge, but rather the systematic development of professional competence.

Hill: What specifically has changed as a result of the redesign?
Mulas: We have structured the program more closely around the reality of decision-making in a family office. The modules do not simply follow individual subject areas but integrate the core areas of expertise: the role and organization of the family officer, law and taxes, corporate and wealth succession, asset allocation and reporting, as well as liquid, real estate-related, and illiquid investments. Above all, what’s new is the stronger learning framework: assessing initial situations, understanding underlying structures, responsibly weighing decisions, and implementing them for the long term. This transforms specialized knowledge into a comprehensive professional understanding.

Markus Hill, FINANZPLATZ FRANKFURT AM MAIN


Hill: Which topics are now essential components of family office training, even though they were previously treated as rather peripheral?
Mulas: In addition to the traditional fields of law, taxes, and wealth structuring, today’s curriculum primarily includes governance, organization, succession processes, risk management, international aspects, asset allocation, reporting, investment governance, and illiquid investments. It is precisely these intersections that are crucial: a tax-efficient structure can be difficult to explain to family members; an investment decision can raise governance or liability issues; and the expertise of external advisors must be integrated without delegating decision-making responsibility. It is precisely these points of intersection that define modern family office work.

Hill: How do you ensure that interdisciplinarity doesn’t remain just another term for thematic breadth?
Mulas: By consistently working at the interfaces. For example, a real estate decision is never just a real estate decision. It can have tax, legal, family, financial, and governance-related consequences. The same applies to succession planning, equity investments, or security issues. The program is designed to train students in precisely this way of thinking: not in silos, but within broader contexts.

Hill: What should a graduate be able to assess or decide more professionally afterward than before?
Mulas: He or she should be able to analyze complex situations in a more structured way. What interests are at play? Which risks are visible, and which are not yet apparent? Which experts need to be involved? Where might there be conflicting goals? And which decision is not only technically sound but also sustainable for the family in the long term? In my view, that is the core of professional family office work.

Hill: The quality of instructors is often touted in continuing education programs. How do you ensure that the course isn’t dominated by product-driven agendas or mere self-promotion?
Mulas: We select speakers based on whether they are technically excellent and, at the same time, have genuine experience with complex wealth, family, or corporate structures. What matters is not just reputation, but the ability to convey knowledge in a practical, application-oriented way. Product-focused presentations do not fit this format. Our participants do not expect sales presentations, but rather guidance, substance, and practical experience—both in the course and at the annual conference.

Hill: The term “Family Officer” is not a protected designation. What can a “ ” certification course achieve in this market?
Mulas: A training program cannot legally protect the term. But it can create transparency. The Certified Family Officer (FvF) designation demonstrates that someone has systematically engaged with the core areas of responsibility, interfaces, and levels of accountability. It does not replace experience, but it establishes a clear qualification profile in a market that is often highly inconsistent.

Hill: When you consider the training program and the annual conference together, what do they offer that a single seminar or a traditional conference cannot?
Mulas: The course lays the professional foundation. The annual conference brings topics up to date, broadens perspectives on new developments, and brings together different viewpoints. The roundtable discussions deepen the exchange in smaller groups. By establishing additional committees and formats—such as the Scientific Advisory Board or the practice-oriented webinar series “Family Office Inside,” which addresses current relevant topics—we have significantly expanded the certification program without arbitrarily broadening the participant base. Taken together, this creates an ongoing professional and networking environment for people who want to engage in family office work seriously and professionally.

Hill: What would you consider a good outcome if someone attends the course and subsequently remains part of this community?
Mulas: That this person not only knows more, but also asks questions differently—in a more professional, structured, and forward-thinking way. Good family office work often begins with asking the right questions before decisions are made. If graduates can identify risks earlier, coordinate specialists more effectively, and manage family wealth in a more holistic manner, then the program has served its purpose. If alumni maintain and further develop the network among their peers on a long-term basis and on their own initiative—that is their additional, lasting benefit.

Hill: Thank you very much for the interview.

Event Announcement: “Annual Family Office 2026 Conference”

Dialogue & Information:

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – CHANNEL

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – GROUP

FUND BOUTIQUES on LINKEDIN – CHANNEL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI Region & FONDSBOUTIQUEN.DE (2026) – Topics, Interests, Dialogue (Selection & “Snapshots”)

February 25, 2026, Frankfurt – “Frankfurt am Main Financial Center Meets Wealth Management”

(Markus Hill – Moderators: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

February 26, 2026, Frankfurt – “Forum for Digital Assets (FDV)”

Editorial Team – Special Feature “Frankfurt am Main Financial Center Meets Wealth Management & Digital Assets”

(Interviews / Guest Contributions, “Support” & MORE: info: markus-hill.com)

March 17, 2026, Frankfurt – Private Markets Excellence Forum – “Private Markets, Family Offices & Foundations – Due Diligence & Outlook 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Managing Director, VIRATIO GmbH)

Interview with Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Spring 2026: Investor Study “Preferences of Institutional Investors in Real Estate & Alternative Investments”

(Markus Hill – Moderator, Podcast: Sebastian Thürmer, “artis & x” – Example 2025)

April 16, 2026 – “köln let’s talk” – Bettina Timmler – Real Estate & Dialogue

(Media Partnership)

May 12, 2026, Frankfurt: “Value Investing & Commodities & MORE”

(Markus Hill – Moderator & brief introduction “Fund Boutiques & the U.S. Formula” – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANCIAL CENTER SWITZERLAND)

June 17, 2026, Zurich: Insights – “Family Offices & Fund Boutiques” – The Mountain Talks Summit – FUNDPLAT

(Presentation – Markus Hill)

September 24, 2026, Lucerne: “Swiss Digital Finance Conference 2026” – Markus Hill (PARTNER) speaks with Jan Carlos Janke, lecturer in Digital Business & Innovation at Lucerne University of Applied Sciences and Arts – Computer Science

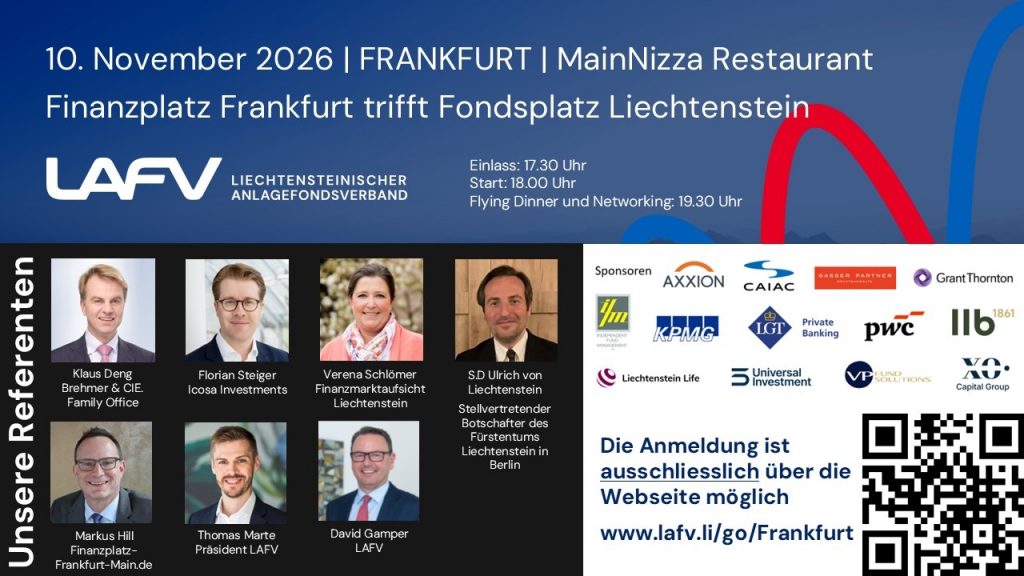
November 10, 2026, Frankfurt: “Frankfurt am Main Financial Center Meets Liechtenstein Financial Center”

(Markus Hill – Moderator – LAFV Liechtenstein Investment Fund Association: Panel & Presentations)

Input, ideas, and suggestions on the topics mentioned above are welcome:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Unsplash & Frankfurt Financial Center

Source: IPE. DA.CH
FINANZPLATZ FRANKFURT & FINANZPLATZ DEUTSCHLAND: „Was muss ein Family Office verstehen, koordinieren und beurteilen können, damit Familienvermögen langfristig professionell begleitet wird?“ (INTERVIEW – Dr. Sigrid Mulas, Geschäftsführerin der Fachseminare von Fürstenberg)

Family Office-Themen haben in den vergangenen Jahren deutlich an Breite gewonnen. Neben klassischen Fragen der Vermögensanlage rücken Governance, Nachfolge, Unternehmensbeteiligungen, internationale Strukturen und die professionelle Koordination unterschiedlicher Experten stärker in den Mittelpunkt. Im Vorfeld der Jahrestagung Family Office 2026 sprach Markus Hill Finanzplatz Frankfurt am Main mit Dr. Sigrid Mulas, Geschäftsführerin der Fachseminare von Fürstenberg, über die Weiterentwicklung der Veranstaltung, die Neukonzeption des Lehrgangs „Zertifizierter Family Officer (FvF)“ und die Frage, welche Kompetenzen Family Officers heute benötigen. Besonders interessant war dabei der Blick auf die Schnittstellen: Family Office-Arbeit erschöpft sich nicht in einzelnen Fachdisziplinen. Entscheidend ist vielmehr, wie rechtliche, steuerliche, finanzielle, familiäre und Governance-Fragen in der Praxis zusammengeführt werden. Das Gespräch gab zugleich Einblicke in die Schwerpunkte der Jahrestagung 2026 in Bad Neuenahr sowie in die Entwicklung eines Fach- und Netzwerkumfelds rund um die Ausbildung zum Zertifizierten Family Officer.

Dr. Sigrid Mulas, Geschäftsführerin der Fachseminare von Fürstenberg

Hill: Frau Dr. Mulas, die Jahrestagung Family Office 2026 steht vor einigen Veränderungen. Was ist neu?
Mulas: Wir entwickeln die Jahrestagung 2026 sichtbar weiter. Zum einen findet sie nach fünf Jahren dieses Jahr in Bad Neuenahr statt. Zum anderen übernimmt Dr. Florian Oppel zusammen mit Dr. Henning Schröer die Tagungsleitung. Damit setzen wir auch inhaltlich einen neuen Akzent. Die Jahrestagung soll noch stärker der Ort werden, an dem aktuelle Family Office-Fragen nicht nur vorgestellt, sondern fachlich eingeordnet und offen diskutiert werden.

Hill: Was unterscheidet Ihre Jahrestagung von klassischen Wealth-Management-, Private-Banking- oder Investmentkonferenzen?
Mulas: Viele Veranstaltungen in diesem Umfeld betrachten Family Offices vor allem als Investoren oder Produktzielgruppe. Das ist uns zu eng. Bei uns geht es um die Gesamtarchitektur komplexer Familienvermögen: Familie, Unternehmen, Vermögen, Governance, Nachfolge, Risiko, Recht, Steuern und Kapitalanlage. Investmentthemen spielen eine Rolle, aber nicht isoliert. Entscheidend ist die Frage: Was muss ein Family Office verstehen, koordinieren und beurteilen können, damit Familienvermögen langfristig professionell begleitet wird?

Hill: Können Sie schon etwas zum Programm 2026 sagen?
Mulas: Ja, das Programm ist inzwischen veröffentlicht und zeigt sehr gut, wohin sich die Jahrestagung entwickelt. Wir beginnen mit der Frage, wie Familienvermögen in Krisenzeiten strategisch gesichert werden kann, und spannen den Bogen dann über Nachfolge- und Strukturmaßnahmen, Immobilien, strategische Asset Allocation, Private Debt und Minderheitsbeteiligungen in Familienunternehmen. Am zweiten Tag stehen stärker die operativen und governancebezogenen Fragen im Mittelpunkt: KI im Family Office, Family Office-Governance, der Beirat sowie Kommunikation und Reputation von Unternehmerfamilien. Damit bildet die Tagung genau die Breite ab, die moderne Family Office-Arbeit heute verlangt: Vermögen, Familie, Unternehmen, Governance, Investments und Risiko müssen zusammengedacht werden.

Markus Hill, FINANZPLATZ FRANKFURT AM MAIN


Hill: Gibt es Programmpunkte, auf die Sie besonders hinweisen würden?
Mulas: Alle Vorträge versprechen spannende Insights, weil sie unterschiedliche Perspektiven auf die Praxis professioneller Family Offices eröffnen. Für ihre Leser dürften aber zwei Themen vielleicht besonders interessant sein: erstens die Strategische Asset Allocation für Unternehmerpersönlichkeiten und Unternehmerfamilien, weil hier Kapitalanlage nicht abstrakt, sondern aus der Denk- und Entscheidungslogik von Prinzipalen betrachtet wird. Zweitens Private Debt, da diese Anlageklasse für Family Offices und andere professionelle Investoren zunehmend relevant wird und eine disziplinierte Einordnung von Rendite, Risiko, Segmenten und Auswahlkriterien verlangt. Ergänzend ist auch der Vortrag zu Minority Investments in Familienunternehmen spannend, weil er Family Equity, langfristige Partnerschaften und Governance-Fragen verbindet. Wichtig bleibt aber: Die Jahrestagung ist nicht nur Vortragsprogramm. Das exklusive Alumni-Treffen der Zertifizierten Family Officer (FvF) und das gemeinsame Abendessen schaffen den Rahmen, in dem die Themen vertraulich weitergedacht werden können.

Hill: Netzwerk ist ein häufiges Versprechen in der Weiterbildungsbranche. Wann wird daraus aus Ihrer Sicht tatsächlich ein fachlicher Mehrwert?
Mulas: Wenn ein Netzwerk nicht beliebig offen ist und auf einer gemeinsamen fachlichen Grundlage beruht. Genau das ist bei unseren Absolventinnen und Absolventen der Fall. Sie haben denselben Lehrgang durchlaufen, teilen ein Grundverständnis professioneller Family Office-Arbeit und begegnen sich anschließend auf der Jahrestagung oder bei Stammtischen wieder. Dadurch entsteht nicht nur Kontakt, sondern Vertrauen – und Vertrauen ist in diesem Bereich eine echte Arbeitsgrundlage.

Hill: Wie groß ist dieser Kreis inzwischen?
Mulas: Seit dem Start des Lehrgangs im Jahr 2017 haben rund 130 Teilnehmerinnen und Teilnehmer den Abschluss Zertifizierter Family Officer (FvF) erworben. Das ist kein Massenformat, sondern ein bewusst gewachsener Kreis. 2026 haben wir den Lehrgang neu konzipiert, weil sich die Anforderungen an Family Officers verändert haben.

Hill: Was war an der bisherigen Konzeption nicht mehr ausreichend?
Mulas: Die Anforderungen an Family Officers haben sich deutlich weiterentwickelt, und wir haben in den vergangenen fast zehn Jahren viel Feedback erhalten und weitere Expertise entwickelt. In der Praxis zeigt sich heute noch stärker, dass professionelle Family Office-Arbeit nicht an fehlendem Fachwissen scheitert, sondern an fehlender Integration: Recht, Steuern, Vermögen, Familie, Governance und Risiko müssen zusammen gedacht werden. Die Themen Wertschöpfung und auch die internationalen Bezüge sind von imminenter Bedeutung. Deshalb haben wir den Lehrgang 2026 grundlegend neu konzipiert – auf Basis vieler Lehrgänge, Rückmeldungen von Teilnehmern und der gewachsenen fachlichen Perspektiven. Ziel ist nicht mehr Wissenssammlung, sondern die systematische Entwicklung professioneller Handlungskompetenz.

Hill: Was hat sich durch die Neukonzeption konkret verändert?
Mulas: Wir haben den Lehrgang stärker entlang der Entscheidungsrealität im Family Office aufgebaut. Die Module folgen nicht einfach einzelnen Fachgebieten, sondern verbinden die zentralen Kompetenzfelder: Rolle und Organisation des Family Officers, Recht und Steuern, Unternehmens- und Vermögensnachfolge, Asset Allocation und Reporting sowie liquide, immobilienbezogene und illiquide Investments. Neu ist vor allem die stärkere Lernlogik: Ausgangslagen erfassen, Strukturen durchdringen, Entscheidungen verantwortungsvoll abwägen und langfristig umsetzen. Damit wird aus Fachwissen ein professionelles Gesamtverständnis.

Hill: Welche Themen gehören heute zwingend in eine Family Office-Ausbildung, obwohl sie früher eher randständig behandelt wurden?
Mulas: Neben den klassischen Feldern Recht, Steuern und Vermögensstrukturierung gehören heute vor allem Governance, Organisation, Nachfolgeprozesse, Risikofragen, internationale Aspekte, Asset Allocation, Reporting, Investment-Governance und illiquide Anlagen dazu. Gerade die Schnittstellen sind entscheidend: Eine steuerlich sinnvolle Struktur kann familiär schwer vermittelbar sein; eine Investmententscheidung kann Governance- oder Haftungsfragen auslösen; externe Beraterkompetenz muss integriert werden, ohne Entscheidungsverantwortung zu delegieren. Genau diese Bruchstellen prägen moderne Family Office-Arbeit.

Hill: Wie verhindern Sie, dass Interdisziplinarität nur ein anderes Wort für thematische Breite bleibt?
Mulas: Indem wir konsequent an Schnittstellen arbeiten. Ein Beispiel: Eine Immobilienentscheidung ist nie nur eine Immobilienentscheidung. Sie kann steuerliche, rechtliche, familiäre, finanzielle und governancebezogene Folgen haben. Ähnlich ist es bei Nachfolge, Beteiligungen oder Sicherheitsfragen. Der Lehrgang soll genau dieses Denken trainieren: nicht in Silos, sondern in Zusammenhängen.

Hill: Was sollte ein Absolvent anschließend professioneller einordnen oder entscheiden können als vorher?
Mulas: Er oder sie sollte komplexe Situationen strukturierter lesen können. Welche Interessen sind im Spiel? Welche Risiken sind sichtbar, welche noch nicht? Welche Fachleute müssen eingebunden werden? Wo drohen Zielkonflikte? Und welche Entscheidung ist nicht nur fachlich korrekt, sondern für die Familie langfristig tragfähig? Das ist aus meiner Sicht der Kern professioneller Family Office-Arbeit.

Hill: Referentenqualität wird in Weiterbildungsformaten oft behauptet. Wie stellen Sie sicher, dass im Lehrgang keine Produktlogik oder reine Selbstdarstellung dominiert?
Mulas: Wir wählen Referentinnen und Referenten danach aus, ob sie fachlich exzellent sind und zugleich echte Erfahrung mit komplexen Vermögens-, Familien- oder Unternehmensstrukturen haben. Entscheidend ist nicht allein Reputation, sondern die Fähigkeit, Wissen anwendungsbezogen zu vermitteln. Produktvorträge passen nicht zu diesem Format. Unsere Teilnehmer erwarten keine Verkaufspräsentationen, sondern Orientierung, Substanz und Praxiserfahrung – sowohl beim Lehrgang als auch der Jahrestagung.

Hill: Der Begriff „Family Officer“ ist nicht geschützt. Was kann ein Zertifikatslehrgang in diesem Markt leisten?
Mulas: Ein Lehrgang kann den Begriff nicht rechtlich schützen. Aber er kann Transparenz schaffen. Der Abschluss Zertifizierter Family Officer (FvF) zeigt, dass sich jemand systematisch mit den zentralen Aufgabenfeldern, Schnittstellen und Verantwortungsebenen auseinandergesetzt hat. Er ersetzt keine Erfahrung, aber er schafft ein nachvollziehbares Qualifikationsprofil in einem Markt, der häufig sehr uneinheitlich ist.

Hill: Wenn Sie den Lehrgang und die Jahrestagung zusammen betrachten: Was entsteht daraus, was ein einzelnes Seminar oder eine klassische Konferenz nicht leisten kann?
Mulas: Der Lehrgang schafft die fachliche Grundlage. Die Jahrestagung aktualisiert Themen, öffnet den Blick für neue Entwicklungen und bringt unterschiedliche Perspektiven zusammen. Die Stammtische vertiefen den Austausch im kleineren Kreis. Mit der Errichtung weiterer Gremien und Formate, z.B. des Wissenschaftlichen Beirats oder der praxisorientierten Webinarserie „Family Office Inside“, in der aktuell relevante Themen aufgegriffen werden, haben wir das Zertifizierungsprogramm deutlich erweitert – ohne den Teilnehmerkreis beliebig zu öffnen. Zusammengenommen entsteht ein fortlaufendes Fach- und Netzwerkumfeld für Menschen, die Family Office-Arbeit ernsthaft und professionell betreiben wollen.

Hill: Was wäre für Sie ein gutes Ergebnis, wenn jemand den Lehrgang besucht und anschließend Teil dieses Kreises bleibt?
Mulas: Dass diese Person nicht nur mehr weiß, sondern anders fragt. Professioneller, strukturierter, vorausschauender. Gute Family Office-Arbeit beginnt oft damit, die richtigen Fragen zu stellen, bevor Entscheidungen getroffen werden. Wenn Absolventinnen und Absolventen Risiken früher erkennen, Spezialisten besser koordinieren und Familienvermögen ganzheitlicher begleiten können, dann erfüllt der Lehrgang seinen Zweck. Wenn die Alumni dauerhaft und eigeninitiativ unter ihresgleichen das Netzwerk pflegen und fortentwickeln – das ist ihr weiterer dauerhafter Gewinn.

Hill: Vielen Dank für das Gespräch.

Veranstaltungshinweis “Jahrestagung Family Office 2026„

Dialog & Information:

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – KANAL

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – GRUPPE

FONDSBOUTIQUEN auf LINKEDIN – KANAL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI-Region & FONDSBOUTIQUEN.DE (2026) – Themen, Interessen, Dialog (Auswahl & „Snapshots“)

25.2.2026, Frankfurt – „Finanzplatz Frankfurt am Main meets Wealthmanagement“

(Markus Hill – Moderation: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

26.2.2026, Frankfurt – „Forum für Digitale Vermögenswerte (FDV)“

Redaktion – Themenspecial „Finanzplatz Frankfurt am Main meets Wealthmanagement & Digital Assets“

(Interviews / Gastbeiträge, “Support” & MORE: info: markus-hill.com)

17.3.2026, Frankfurt – Private Markets Excellence Forum – „Private Markets, Family Offices & Stiftungen – Due Diligence & Ausblick 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Geschäftsführer, VIRATIO GmbH)

Interview mit Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Frühjahr 2026: Investorenstudie „Präferenzen institutioneller Investoren bei Immobilien & Alternative Investments“

(Markus Hill – Moderation, Podcast: Sebastian Thürmer, “artis & x” – Beispiel 2025)

16.4.2026 – „köln let’s talk“ – Bettina Timmler – Immobilien & Dialog

(Medienpartnerschaft)

12.5.2026, Frankfurt: „Value Investing & Rohstoffe & MORE“

(Markus Hill – Moderation & Kurzintro „Fondsboutiquen & USA-Formel“ – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANZPLATZ SCHWEIZ)

17.6.2026, Zürich: Insights – “Family Offices & Fondsboutiquen” – The Mountain Talks Summit – FUNDPLAT

(Vortrag – Markus Hill)

24.9.2026, Luzern: „Swiss Digital Finance Conference 2026“ – Markus Hill (PARTNER) spricht mit Jan Carlos Janke, Dozent im Themenfeld Digital Business & Innovation der Hochschule Luzern – Informatik

10.11.2026, Frankfurt: „Finanzplatz Frankfurt am Main meets Finanzplatz Liechtenstein“

(Markus Hill – Moderation – LAFV Liechtensteinischer Anlagefondsverband: Panel & Vorträge)

Input, Ideen & Anregungen zu den oben genannten Themen sind willkommen:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Unsplash & Finanzplatz Frankfurt

Quelle: IPE. DA.CH

FRANKFURT AM MAIN AS A FINANCIAL CENTER: “We are therefore currently experiencing a market-driven correction in the real estate asset class, which may continue for some time to come” – (INTERVIEW – Sebastian Thürmer, Artis Institutional Capital)

Institutional investors remain committed to real estate, but their appetite for new investments has declined significantly. At the same time, infrastructure and select segments of private debt are coming more into focus. The sixth edition of the study “Institutional Investors’ Preferences in Real Estate and Alternative Investments” thus paints a nuanced picture: high real estate allocations are met with growing caution, while energy, transportation, digital, and social infrastructure are gaining in appeal. For the first time, the study also examines how institutional investors view artificial intelligence and tokenization. In a conversation with Markus Hill, Sebastian Thürmer explains the key findings of the survey of 51 investors who collectively manage assets totaling 1.074 trillion euros (Part 1 of 2).

Hill: Mr. Thürmer, can you briefly summarize the key findings of your study, “Preferences of Institutional Investors in Real Estate and Alternative Investments,” now in its sixth edition?

Thürmer: For the study, we surveyed 51 institutional investors about their past investments and future considerations in the areas of real estate and alternative investments. Other topics included sustainability and, for the first time, the use of artificial intelligence and tokenization. In total, the surveyed participants manage assets totaling 1.074 trillion euros. Nearly 60 percent of the participants are insurance companies or pension funds. This means the proportion of traditional institutional investors is very high. Other investor groups include family offices, foundations, banks, savings banks, and industrial companies.

In real estate, the brief reversal seen in 2025 appears to have already come to an end. The appetite for new investments is currently low. Reasons likely include economic challenges, rising interest rates, and new competition from infrastructure projects. Real estate allocations remain high but are not being further expanded.

The outlook is better for alternative investments. Infrastructure investments in the energy, transportation, digital, and social sectors are in demand. Certain segments of private debt—particularly corporate debt and infrastructure debt—are also likely to see increased allocations. We also received interesting responses regarding sustainability as well as, for the first time, AI and tokenization.

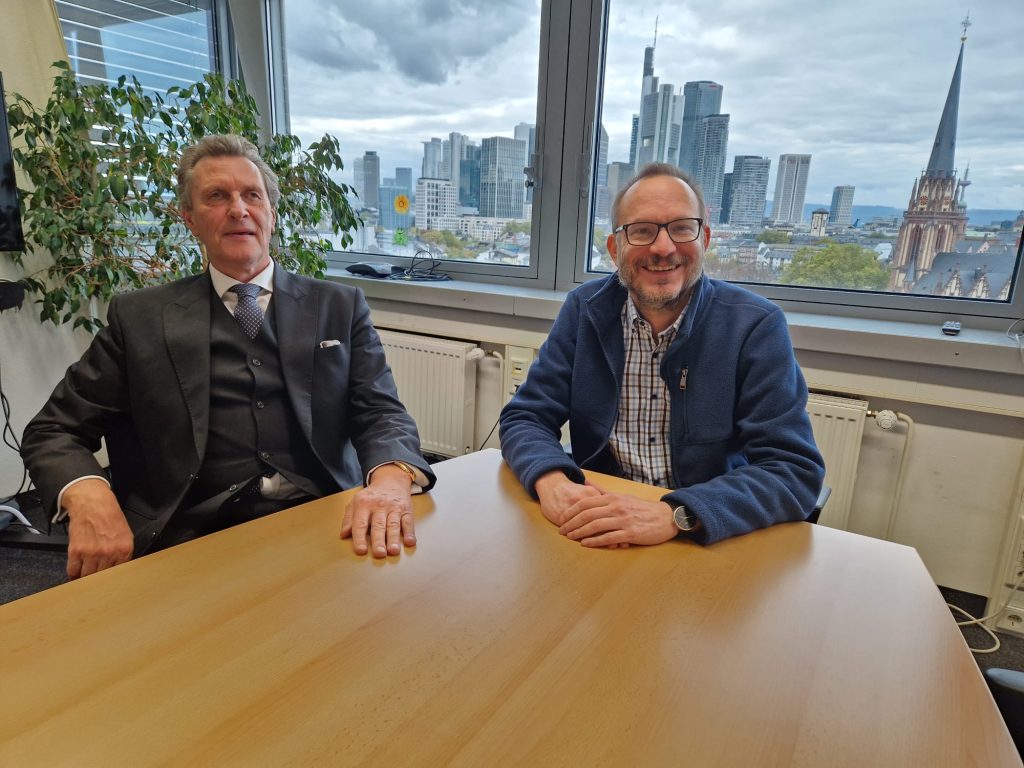
Sebastian Thürmer, Artis Institutional Capital & Markus Hill, Finanzplatz Frankfurt am Main

Hill: Let’s turn to the assessment of the real estate asset class. You mention a waning interest in “concrete gold.” Are real estate investments still a preferred asset class for institutional investors at all?

Thürmer: Real estate certainly remains a preferred asset class. After all, 60 percent of the investors surveyed hold between 5 and 15 percent of their assets in real estate. Another 40 percent have real estate allocations ranging from 15 to over 30 percent. Between 2010 and 2020, the real estate allocation doubled for various reasons. As a result, we are currently experiencing a market-driven correction in the real estate asset class, which may continue for some time to come. Only 8 percent of the investors surveyed are planning to increase their holdings. 68 percent do not anticipate any changes, while 24 percent are considering reducing their holdings. This latter percentage is relatively high compared to previous years.

Hill: That sounds rather pessimistic!

Thürmer: The markets are indeed in crisis mode. The trend is clearly shifting toward core real estate, following a sharp increase in write-downs in recent years. Structural risks in particular—such as those in regions with a high proportion of industry—are now being assessed more critically. Another new factor in the risk assessment of domestic real estate markets is sensitivity to political and economic risks. Many investors see trends toward deindustrialization and, as a result, declining real estate markets. Rising construction costs due to higher raw material prices, climate change, new building codes, and steadily rising financing costs are placing a disproportionate burden on this asset class. Added to this are new competitors in the illiquid investments segment, such as infrastructure investments.

Hill: What types of properties are in demand?

Thürmer: There is interest in social and healthcare real estate—in other words, what tends to be referred to as “social infrastructure.” Residential properties, as a recession-resistant use type, and logistics are also viewed positively. Commercial real estate, such as offices and retail, on the other hand, plays hardly any role at all in new investments.

Hill: How do institutional investors plan to handle existing properties that are not yet up to the latest energy efficiency standards?

Thürmer: 47 percent intend to retrofit their existing properties for energy efficiency or have already done so. 22 percent plan to sell their portfolios. 26 percent are not currently considering any specific measures. However, there are significant differences among investor groups. Churches and insurers are setting an exemplary standard. Banks, savings banks, and pension funds are also active. Nevertheless, many investors view energy-efficiency retrofits as a costly obstacle.

Hill: Do investors still plan to make additional purchases of properties that haven’t undergone energy-efficiency renovations in the future?

Thürmer: 18 percent of the investors surveyed plan such acquisitions. 27 percent do not rule out purchasing properties that have not undergone energy-efficiency renovations. The majority—56 percent—have not yet made up their minds on this issue.

Hill: How are the changing interest rate and financing conditions affecting the investment decisions of institutional investors?

Thürmer: The current interest rate environment is leading to cautious interest rate and return forecasts. Investors must factor in rising financing costs. Over time, this is likely to lead to lower debt-to-equity ratios. This trend is already noticeable in the real estate sector. Sustainable, energy-efficient, and future-proof real estate concepts now have better and more affordable access to debt financing than properties that have not undergone energy-efficiency renovations.

Hill: What criteria do institutional investors consider when selecting a fund or a fund manager prior to making an investment decision?

Thürmer: Institutional investors expect a compelling investment strategy, a strong track record, and a robust deal flow, as well as—where applicable—an initial portfolio that can be implemented promptly. In addition, they look for professional financial management, meaningful reporting, transparency, and ongoing communication throughout the entire investment period.

Hill: In 2026, you expanded your scope of inquiry to include areas such as AI and tokenization. In which areas is AI being used, and to what extent is it already influencing the investment decisions of institutional investors?

Thürmer: AI is primarily used in research and financial analysis (21 percent), risk management (17 percent), and compliance (15 percent). It has played a lesser role so far in allocation decisions, currency management, and portfolio construction. Only 4 percent state that AI directly contributes to investment decisions. 43 percent incorporate AI results into their considerations, while 53 percent have not yet integrated AI.

Hill: In which areas do institutional investors see the greatest benefits of tokenization, and how do they assess its significance for the next five years?

Thürmer: In principle, tokenization is likely to offer advantages in terms of lower barriers to entry, the efficiency of processing and settlement, as well as transparency and reporting. At present, however, only about 18 percent of respondents consider tokenization to be of high or very high importance. 82 percent view it more as a niche application or attribute only minor importance to it.

Hill: Thank you very much for the interview.

LINK TO THE PANEL DISCUSSION / VIDEO “Preferences of Institutional Investors in Real Estate and Alternative Investments”:

Dialogue & Information:

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – CHANNEL

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – GROUP

FONDSBOUTIQUEN on LINKEDIN – CHANNEL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI Region & FONDSBOUTIQUEN.DE (2026) – Topics, Interests, Dialogue (Selection & “Snapshots”)

February 25, 2026, Frankfurt – “Frankfurt am Main Financial Center Meets Wealth Management”

(Markus Hill – Moderator: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

February 26, 2026, Frankfurt – “Forum for Digital Assets (FDV)”

Editorial Team – Special Feature: “Frankfurt am Main as a Financial Center Meets Wealth Management & Digital Assets”

(Interviews / Guest Contributions, “Support” & MORE: info: markus-hill.com)

March 17, 2026, Frankfurt – Private Markets Excellence Forum – “Private Markets, Family Offices & Foundations – Due Diligence & Outlook 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Managing Director, VIRATIO GmbH)

Interview with Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Spring 2026: Investor Study “Preferences of Institutional Investors in Real Estate & Alternative Investments”

(Markus Hill – Moderator, Podcast: Sebastian Thürmer, “artis & x” – Example 2025)

April 16, 2026 – “köln let’s talk” – Bettina Timmler – Real Estate & Dialogue

(Media Partnership)

May 12, 2026, Frankfurt: “Value Investing & Commodities & MORE”

(Markus Hill – Moderator & brief introduction “Fund Boutiques & the U.S. Formula” – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANCIAL CENTER SWITZERLAND)

June 17, 2026, Zurich: Insights – “Family Offices & Fund Boutiques” – The Mountain Talks Summit – FUNDPLAT

(Presentation – Markus Hill)

September 24, 2026, Lucerne: “Swiss Digital Finance Conference 2026” – Markus Hill (PARTNER) speaks with Jan Carlos Janke, lecturer in Digital Business & Innovation at Lucerne University of Applied Sciences and Arts – Computer Science

November 10, 2026, Frankfurt: “Frankfurt am Main Financial Center Meets Liechtenstein Financial Center”

(Markus Hill – Moderator – LAFV Liechtenstein Investment Fund Association: Panel & Presentations)

Input, ideas, and suggestions on the topics mentioned above are welcome:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay & Frankfurt Financial Center

Quelle: IPE DA.CH

FINANZPLATZ FRANKFURT AM MAIN & RESEARCH: „Derzeit erleben wir daher eine marktbedingte Bereinigung bei der Asset-Klasse Immobilien, die möglicherweise noch längere Zeit anhalten wird“ – (INTERVIEW – Sebastian Thürmer, Artis Institutional Capital)

Institutionelle Investoren bleiben bei Immobilien engagiert, doch der Appetit auf Neuinvestitionen ist deutlich gesunken. Gleichzeitig rücken Infrastruktur und ausgewählte Segmente von Private Debt stärker in den Fokus. Die zum sechsten Mal durchgeführte Studie „Präferenzen institutioneller Anleger bei Immobilien und Alternativen Investments“ zeichnet damit ein differenziertes Bild: hohe Immobilienquoten treffen auf wachsende Zurückhaltung, während Energie-, Verkehrs-, Digital- und Sozialinfrastruktur an Attraktivität gewinnen. Erstmals beleuchtet die Untersuchung zudem, wie institutionelle Anleger Künstliche Intelligenz und Tokenisierung einschätzen. Sebastian Thürmer erläutert im Gespräch mit Markus Hill die zentralen Ergebnisse der Befragung von 51 Investoren, die zusammen ein Anlagevolumen von 1,074 Billionen Euro verantworten (Teil 1 von 2).

Hill: Herr Thürmer, können Sie uns kurz und knapp die wichtigsten Ergebnisse Ihrer nun zum sechsten Mal durchgeführten Studie „Präferenzen institutioneller Anleger bei Immobilien und Alternativen Investments“ nennen?

Sebastian Thürmer, Artis Institutional Capital & Markus Hill, Finanzplatz Frankfurt am Main

Thürmer: Für die Studie haben wir 51 institutionelle Investoren zu ihren bisherigen Investments und künftigen Überlegungen in den Bereichen Immobilien und Alternative Investments befragt. Weitere Themen waren Nachhaltigkeit sowie erstmals auch der Einsatz von Künstlicher Intelligenz und Tokenisierung. Insgesamt verantworten die befragten Teilnehmer ein Anlagevolumen von 1,074 Billionen Euro. Fast 60 Prozent der Teilnehmer sind Versicherungsunternehmen oder Altersvorsorgeeinrichtungen. Damit ist der Anteil klassischer institutioneller Investoren sehr hoch. Weitere Anlegergruppen sind unter anderem Family Offices, Stiftungen, Banken, Sparkassen und Industrieunternehmen.

Bei Immobilien scheint die kurze Umkehrbewegung des Jahres 2025 bereits wieder beendet zu sein. Der Appetit auf Neuinvestitionen ist derzeit gering. Gründe dürften konjunkturelle Probleme, steigende Zinsen und die neue Konkurrenz durch Infrastrukturprojekte sein. Die Immobilienquoten bleiben hoch, werden aber nicht weiter ausgebaut.

Bei den Alternativen Investments sieht es besser aus. Gefragt sind Infrastrukturanlagen in den Bereichen Energie, Verkehr, Digitales und Soziales. Auch Teilbereiche von Private Debt, insbesondere Corporate Debt und Infrastructure Debt, dürften aufgestockt werden. Bei den Themen Nachhaltigkeit sowie erstmals KI und Tokenisierung erhielten wir ebenfalls spannende Antworten.

Hill: Kommen wir zur Einschätzung der Assetklasse Immobilien. Sie sprechen von einem nachlassenden Interesse an Betongold. Sind Immobilienanlagen überhaupt noch eine präferierte Assetklasse für institutionelle Investoren?

Thürmer: Immobilien bleiben sicherlich eine präferierte Assetklasse. Immerhin halten 60 Prozent der befragten Anleger zwischen fünf und 15 Prozent ihrer Assets in Immobilien. Weitere 40 Prozent weisen Immobilienquoten von 15 bis über 30 Prozent auf. In den Jahren 2010 bis 2020 hat sich die Immobilienquote aus unterschiedlichen Gründen verdoppelt. Derzeit erleben wir daher eine marktbedingte Bereinigung bei der Asset-Klasse Immobilien, die möglicherweise noch längere Zeit anhalten wird. Aufstockungen planen nur noch acht Prozent der befragten Investoren. 68 Prozent sehen keine Änderungen vor, während 24 Prozent Bestandsreduzierungen erwägen. Letzterer Anteil ist im Vergleich zu den Vorjahren relativ hoch.

Hill: Das hört sich eher pessimistisch an!

Thürmer: Die Märkte befinden sich tatsächlich im Krisenmodus. Der Trend geht klar in Richtung Core-Immobilien, nachdem die Wertberichtigungen in den vergangenen Jahren stark zugenommen haben. Insbesondere strukturelle Risiken, etwa in Regionen mit hohem Industrieanteil, werden inzwischen kritischer beurteilt. Neu bei der Risikobewertung heimischer Immobilienmärkte ist außerdem die Sensibilität für politische und konjunkturelle Risiken. Viele Investoren sehen Tendenzen einer Deindustrialisierung und damit einhergehend rückläufige Immobilienmärkte. Steigende Baukosten infolge höherer Rohstoffpreise, der Klimawandel, neue Bauvorschriften und weiter steigende Finanzierungskosten belasten diese Assetklasse überproportional. Hinzu kommen neue Wettbewerber im Segment der illiquiden Anlagen, beispielsweise Infrastrukturinvestments.

Hill: Welche Nutzungsarten werden nachgefragt?

Thürmer: Interesse besteht an Sozial- und Gesundheitsimmobilien, also tendenziell an „sozialer Infrastruktur“. Auch Wohnen als konjunkturresistente Nutzungsart und Logistik werden positiv gesehen. Gewerbeimmobilien wie Büro und Handel spielen bei Neuanlagen dagegen kaum noch eine Rolle.

Hill: Wie planen institutionelle Investoren mit Bestandsimmobilien umzugehen, die energetisch noch nicht auf dem neuesten Stand sind?

Thürmer: 47 Prozent wollen ihre Bestandsimmobilien energetisch sanieren oder haben dies bereits getan. 22 Prozent planen den Verkauf von Beständen. 26 Prozent denken zunächst nicht über konkrete Maßnahmen nach. Allerdings gibt es große Unterschiede zwischen den Anlegergruppen. Vorbildlich agieren Kirchen und Versicherer. Auch Banken, Sparkassen und Altersvorsorgeeinrichtungen sind aktiv. Dennoch werden energetische Sanierungen von vielen Anlegern als kostenträchtiger Hemmschuh betrachtet.

Hill: Planen Anleger künftig noch Zukäufe bei nicht energetisch sanierten Liegenschaften?

Thürmer: 18 Prozent der befragten Investoren planen solche Zukäufe. 27 Prozent schließen Käufe nicht energetisch sanierter Liegenschaften aus. Die Mehrheit von 56 Prozent hat sich bei diesem Thema noch nicht festgelegt.

Hill: Wie wirken sich die veränderten Zins- und Finanzierungsbedingungen auf die Investitionsentscheidungen institutioneller Investoren aus?

Thürmer: Das derzeitige Zinsumfeld führt zu zurückhaltenden Zins- und Renditeprognosen. Anleger müssen wachsende Finanzierungskosten einkalkulieren. Im Laufe der Zeit dürfte dies zu geringeren Fremdkapitalquoten führen. Im Immobilienbereich ist diese Entwicklung bereits spürbar. Nachhaltige, energieeffiziente und zukunftsfähige Immobilienkonzepte erhalten inzwischen besseren und günstigeren Zugang zu Fremdkapital als nicht energetisch sanierte Liegenschaften.

Hill: Mit welchen Kriterien bei der Fondsselektion beziehungsweise der Auswahl eines Fondsmanagers beschäftigen sich institutionelle Investoren im Vorfeld einer Investmententscheidung?

Thürmer: Institutionelle Investoren erwarten ein überzeugendes Konzept, einen starken Track Record und belastbaren Dealflow sowie gegebenenfalls ein zeitnah umsetzbares Startportfolio. Hinzu kommen professionelles Controlling, aussagekräftiges Reporting, Transparenz und eine laufende Kommunikation während der gesamten Investmentperiode.

Hill: Sie haben 2026 Ihr Frageuniversum um Bereiche wie KI und Tokenisierung erweitert. In welchen Aufgabenfeldern wird KI eingesetzt, und inwiefern beeinflusst sie bereits die Anlageentscheidungen institutioneller Investoren?

Thürmer: KI wird hauptsächlich in Research und Finanzanalyse (21 Prozent), im Risikomanagement (17 Prozent) sowie in der Compliance (15 Prozent) eingesetzt. Bei Allokationsfragen, im Währungsmanagement und in der Portfoliokonstruktion spielt sie bislang eine geringere Rolle. Nur vier Prozent geben an, dass KI unmittelbar zur Anlageentscheidung beiträgt. 43 Prozent lassen KI-Ergebnisse in ihre Überlegungen einfließen, während 53 Prozent KI bislang nicht einbinden.

Hill: In welchen Bereichen sehen institutionelle Investoren den größten Nutzen der Tokenisierung, und wie beurteilen sie deren Bedeutung für die kommenden fünf Jahre?

Thürmer: Grundsätzlich dürfte Tokenisierung Vorteile bei niedrigeren Einstiegshürden, der Effizienz von Abwicklung und Settlement sowie bei Transparenz und Reporting bieten. Zum heutigen Zeitpunkt messen allerdings nur rund 18 Prozent der Befragten der Tokenisierung eine hohe oder sehr hohe Bedeutung bei. 82 Prozent betrachten sie eher als Nischenanwendung oder schreiben ihr nur eine geringe Bedeutung zu.

Hill: Vielen Dank für das Gespräch.

LINK ZUR PANELDISKUSSION / VIDEO „„Präferenzen institutioneller Anleger bei Immobilien und Alternativen Investments““:

Dialog & Information:

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – KANAL

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – GRUPPE

FONDSBOUTIQUEN auf LINKEDIN – KANAL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI-Region & FONDSBOUTIQUEN.DE (2026) – Themen, Interessen, Dialog (Auswahl & „Snapshots“)

25.2.2026, Frankfurt – „Finanzplatz Frankfurt am Main meets Wealthmanagement“

(Markus Hill – Moderation: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

26.2.2026, Frankfurt – „Forum für Digitale Vermögenswerte (FDV)“

Redaktion – Themenspecial „Finanzplatz Frankfurt am Main meets Wealthmanagement & Digital Assets“

(Interviews / Gastbeiträge, “Support” & MORE: info: markus-hill.com)

17.3.2026, Frankfurt – Private Markets Excellence Forum – „Private Markets, Family Offices & Stiftungen – Due Diligence & Ausblick 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Geschäftsführer, VIRATIO GmbH)

Interview mit Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Frühjahr 2026: Investorenstudie „Präferenzen institutioneller Investoren bei Immobilien & Alternative Investments“

(Markus Hill – Moderation, Podcast: Sebastian Thürmer, “artis & x” – Beispiel 2025)

16.4.2026 – „köln let’s talk“ – Bettina Timmler – Immobilien & Dialog

(Medienpartnerschaft)

12.5.2026, Frankfurt: „Value Investing & Rohstoffe & MORE“

(Markus Hill – Moderation & Kurzintro „Fondsboutiquen & USA-Formel“ – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANZPLATZ SCHWEIZ)

17.6.2026, Zürich: Insights – “Family Offices & Fondsboutiquen” – The Mountain Talks Summit – FUNDPLAT

(Vortrag – Markus Hill)

24.9.2026, Luzern: „Swiss Digital Finance Conference 2026“ – Markus Hill (PARTNER) spricht mit Jan Carlos Janke, Dozent im Themenfeld Digital Business & Innovation der Hochschule Luzern – Informatik

10.11.2026, Frankfurt: „Finanzplatz Frankfurt am Main meets Finanzplatz Liechtenstein“

(Markus Hill – Moderation – LAFV Liechtensteinischer Anlagefondsverband: Panel & Vorträge)

Input, Ideen & Anregungen zu den oben genannten Themen sind willkommen:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay & Finanzplatz Frankfurt

Quelle: IPE. DA.CH

FRANKFURT FINANCIAL CENTER & SWISS FINANCIAL CENTER: High-Value Assets – History, Networks, Trust, and Looking Beyond Asset Classes (INTERVIEW – Tobias Heining, Martin Fiddler Aviation)

The Frankfurt am Main financial center engages in a discussion with Markus Schwingshackl of PRIVATE KEY NETWORK in Zurich and recommends exchanging ideas with an interesting networker from Zurich. We were happy to take up the challenge. At first glance, business jets, yachts, art, real estate, precious metals, and wealth management seem like separate worlds. In reality, however, they often raise the same questions among entrepreneurial families, private clients, and UHNWIs: Who can you trust? Who understands complex assets? And where can a professionally sound exchange take place beyond traditional industry boundaries?

Tobias Heining is familiar with both the world of major international law firms and the unique requirements surrounding high-value mobile assets. Through the High Value Assets Roundtables, he brings together experts, providers, and influencers from various asset classes. In conversation with Markus Hill, he discusses his unusual career path, the work of Martyn Fiddler, and why a good network thrives not on hoarding but on sharing.

Hill: From studying history to the world of major law firms to business jets and yachts—a résumé you could hardly make up. Who is the person behind it all, and what makes him tick?

Tobias Heining, Martin Fiddler Aviation

Heining: When I earned my master’s degree in 2001, I started working at a PR agency that, among other things, advised major law firms and accounting firms on public relations matters. At the time, that was still a relatively niche but exciting and challenging field of work. From there, my path led me to the client side, working with major U.S., British, and German law firms. There, I held various positions, eventually leading large teams with corresponding budget responsibility in the areas of business development, marketing, and communications.

It’s not a big leap from business development and strategic positioning to innovation, new business models, and more efficient processes and administrative functions. As a leader, I want to understand markets, structures, and processes and drive change to make a company fit for the future. In the age of artificial intelligence, this is likely one of the central challenges. This is precisely what motivates me: I see myself as a strategist, networker, and innovator.

Despite my enthusiasm for change, a human touch and maintaining my personal integrity have remained important to me. At first glance, these may not always seem entirely compatible. The move into business aviation and yachting came as a surprise to me as well. However, it has proven to be a particularly refreshing and enriching experience. The DNA of these industries is fundamentally collaborative and characterized by a high degree of pragmatism and openness. That requires a great deal of mental flexibility—and that’s exactly what I like.

Hill: Business aviation and yachting sound exciting, but also a little nebulous. What exactly does the company you work for do?

Heining: “Vague” is a nice word to use in this context. We help our clients safely navigate some of the pitfalls of business aviation and yachting. For more than 40 years, Martyn Fiddler has been a boutique firm specializing in tailored international solutions—particularly for owners and operators of complex mobile assets such as business jets, helicopters, and yachts.

Markus Hill, Finanzplatz Frankfurt & Tobias Heining, Martin Fiddler Aviation

At its core, Martyn Fiddler is a corporate service provider—that is, a provider and administrator of special-purpose entities. In addition, we offer specialized tax consulting and support for all customs-related matters, such as the import and export of assets. We also maintain a global ecosystem of close partners and contacts. This enables us to guide our clients on practical issues beyond our own service portfolio and connect them with suitable professional contacts.

Hill: You’ve earned a reputation as a thought leader, pioneer, and networker in various market segments—for example, in the legal market by being an early adopter of legal technology. Now you’re active in the business jet and yacht sectors. What drives you to innovate, and how did the idea for the High Value Assets Roundtables come about?

Heining: I firmly believe in the power of constructive exchange and the sharing of experiences. For me, the starting point for any networking initiative is therefore always a communication gap between certain individuals or groups. If bridging that gap promises mutual benefits and synergies, a genuine opportunity arises. That was the case when the European Legal Technology Association—ELTA for short—was founded ten years ago, and it was the same with the High Value Assets Roundtables.

The establishment of the first legal tech department at a major German law firm, which I initiated in 2014, was the starting point for me to look beyond the German market. But as is so often the case in Europe, people in Germany knew very little about developments in France, Spain, Italy, the Netherlands, or Central and Eastern Europe—and vice versa. In the United Kingdom, too, there was only limited awareness of developments across the English Channel. With ELTA, we wanted to bring together the various innovators and innovation hubs and create a cross-border platform for sharing experiences.

When I moved into business aviation and yachting in 2023, I quickly realized that although the target audiences overlap significantly and the operational and market-related challenges are similar, there was no structured dialogue between representatives of different asset classes, vendors, and service providers in the luxury, private client, and UHNWI sectors. A corresponding platform was also lacking in the DACH region. With the High Value Assets Roundtables, I wanted to close this gap. I consider this a fruitful approach for all involved.

Hill: What exactly is it about, and what makes the High Value Assets Network interesting?

Heining: The networking platform launched last year with two events in May and October 2025 in Berlin. Two more events have already followed this year: one in April in Germany and one in June 2026 in Austria. Our upcoming event on September 10 in Zurich rounds out this year’s roundtable activities in the DACH region.

Markus Hill, Finanzplatz Frankfurt & Markus Schwingshackl, Centro LAW

The platform is designed to facilitate and promote professional exchange among representatives of various asset classes, as well as providers and service providers in the luxury, private client, and UHNWI sectors. We all thrive on the strength, breadth, and depth of our networks. At the same time, we rely on trusted influencers with access to the relevant target groups.

At previous High Value Assets Roundtables, guests have represented the fields of business aviation, yachting, real estate, automotive, gemstones and precious metals, wealth management, art and culture, private client services, financing, insurance, law and taxes, as well as security architecture. In addition to topics relevant to these target groups, the discussions consistently focus on the unique characteristics and market specifics of the various asset classes. Equally important is the exchange of experiences regarding comparable operational challenges and potential solutions. In this way, we simultaneously broaden our horizons and expand the reach of our networks.

Hill: Who are the participants, and how can one join?

Heining: At the various events so far, we’ve been able to bring together up to 70 guests. That’s a good size for a networking format. If the group gets any larger, it quickly becomes unwieldy—and I don’t want to turn the format into a conference. The most recent High Value Assets Roundtable near Vienna, however, was significantly larger. That was due to the excellent cooperation with the Austrian Business Aviation Association (ABAA).

The participant group typically consists of experienced representatives from various asset classes, as well as providers and service providers from the aforementioned segments. Two criteria are paramount in the selection process. On the professional side, these include in-depth professional experience and expertise in the luxury, private clients, and UHNWI sectors, a robust network of high-quality contacts, and a willingness to share knowledge and contacts in the interest of all participants.

On the personal side, it’s about embracing new ideas, looking beyond one’s professional horizons, and being willing to expand one’s own experience through friendly exchanges with like-minded individuals. This requires openness, authenticity, a certain degree of humility, and a positive attitude. Sustainable success in a network can only be achieved if one is willing to invest personally and, on occasion, to go the extra mile. Those who wish only to take but not to give do not belong in this network. This likely also applies to people who consider themselves something very special and superior.

Participation is generally by personal invitation from me. I ask those invited to contact me briefly if they’d like to send someone else or suggest additional potential participants. This helps ensure that the exchange of experiences and the quality of the network remain at a consistently high level.

Hill: What are the plans for the future of the network?

Heining: Participants from across the DACH region are already expressly welcome and well-represented at all events. Given the international nature of our markets and target groups, I’d particularly like to further strengthen cross-border networking among these circles. This also includes expanding the network internationally—for example, to London or Monaco. That’s on the agenda, at least for the coming year.

My particular focus, however, remains on attracting new and exciting people to the network and further deepening connections within the individual asset classes and service areas. With a steadily growing network, we will likely also need to consider further professionalizing our structures and, if necessary, adjusting the distribution of responsibilities with potential cooperation partners.

Hill: Thank you very much for the interview. We’re looking forward to the panel discussion with Markus Schwingshackl and wish you every success for the evening in Zurich!

Impression & Philosophy, “Flavor” of the Evening in Zurich (Quote – Tobias Heining):

“As part of our ongoing efforts to encourage meaningful networking among participants, I would be delighted if you could share one question about your business that you would most like fellow attendees to ask you. Rather than a general question such as ‘What exactly does your company do?’ 😌, please consider something more insightful and specific. For example, it could relate to your unique value proposition, the business challenges you help solve, the market segments you serve, or even what really motivates you to go the extra mile or ways in which others could support your business growth.”

Panel Discussion (3:00 p.m., September 10, 2026): Virtual Values – High-Value Assets in the Digital Space

Participants: Moderator: Frank Liemandt is the managing director of the German Helicopter Association and organizer of European Rotors, Europe’s largest helicopter trade show. He is also a professional moderator and created the video interview series “Fly Me to the Top.”

Marco Infuso, Head of Digital Assets Sales for Central Europe, Apex Group.

Markus Schwingshakl is a private clients attorney who advises entrepreneurs, family offices, and high-net-worth individuals. He is also a co-founder of the PKN Private Key Network, a network established in 2025 for professionals in the fields of private wealth, digital assets, and AI, which aims to shape industry standards and foster collaboration among experts.

Robin Kretzschmar is the founder of 7Assets. The team strives to simplify and improve asset management through the use of artificial intelligence and to create a platform that serves private investors, financial advisors, and institutions alike, ultimately helping to optimize asset flows.

Hannes Gurzki is a recognized expert in luxury brand management and marketing who teaches at the International University of Monaco, ESSEC Business School, and the Technical University of Braunschweig. As Program Director at ESMT Berlin, he also works with leading global companies and luxury brands from various sectors on value creation strategies. Hannes has previously published an article on “Luxury Brands in the Digital Space” in the Harvard Business Review.

LinkedIn-Profil von Tobias Heining:

Tobias Heining

Dialogue & Information:

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – CHANNEL

FRANKFURT AM MAIN FINANCIAL CENTER on LINKEDIN – GROUP

FUND BOUTIQUES on LINKEDIN – CHANNEL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI Region & FONDSBOUTIQUEN.DE (2026) – Topics, Interests, Dialogue (Selection & “Snapshots”)

February 25, 2026, Frankfurt – “Frankfurt am Main Financial Center Meets Wealth Management”

(Markus Hill – Moderators: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

February 26, 2026, Frankfurt – “Forum for Digital Assets (FDV)”

Editorial Team – Special Feature “Frankfurt am Main Financial Center Meets Wealth Management & Digital Assets”

(Interviews / Guest Contributions, “Support” & MORE: info: markus-hill.com)

March 17, 2026, Frankfurt – Private Markets Excellence Forum – “Private Markets, Family Offices & Foundations – Due Diligence & Outlook 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Managing Director, VIRATIO GmbH)

Interview with Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Spring 2026: Investor Study “Preferences of Institutional Investors in Real Estate & Alternative Investments”

(Markus Hill – Moderator, Podcast: Sebastian Thürmer, “artis & x” – Example 2025)

April 16, 2026 – “köln let’s talk” – Bettina Timmler – Real Estate & Dialogue

(Media Partnership)

May 12, 2026, Frankfurt: “Value Investing & Commodities & MORE”

(Markus Hill – Moderator & brief introduction “Fund Boutiques & the U.S. Formula” – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANCIAL CENTER SWITZERLAND)

June 17, 2026, Zurich: Insights – “Family Offices & Fund Boutiques” – The Mountain Talks Summit – FUNDPLAT

(Presentation – Markus Hill)

September 24, 2026, Lucerne: “Swiss Digital Finance Conference 2026” – Markus Hill (PARTNER) speaks with Jan Carlos Janke, lecturer in Digital Business & Innovation at Lucerne University of Applied Sciences and Arts – Computer Science

November 10, 2026, Frankfurt: “Frankfurt am Main Financial Center Meets Liechtenstein Financial Center”

(Markus Hill – Moderator – LAFV Liechtenstein Investment Fund Association: Panel & Presentations)

Input, ideas, and suggestions on the topics mentioned above are welcome:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay & Finanzplatz Frankfurt

FINANZPLATZ FRANKFURT & FINANZPLATZ SCHWEIZ: High Value Assets – Geschichte, Netzwerke, Vertrauen und der Blick über Asset-Klassen hinaus (INTERVIEW – Tobias Heining, Martin Fiddler Aviation)

Finanzplatz Frankfurt am Main tauscht sich mit Markus Schwingshackl von PRIVATE KEY NETWORK in Zürich aus und empfiehlt den Gedankenaustausch mit einem interessanten Netzwerker aus Zürich. Gerne haben wir den Ball aufgenommen. Business Jets, Yachten, Kunst, Immobilien, Edelmetalle und Wealth Management wirken auf den ersten Blick wie getrennte Welten. Tatsächlich treffen sie bei Unternehmerfamilien, Private Clients und UHNWIs häufig auf dieselben Fragen: Wem kann man vertrauen? Wer versteht komplexe Vermögenswerte? Und wo findet ein fachlich belastbarer Austausch jenseits klassischer Branchengrenzen statt? Tobias Heining kennt sowohl die Welt internationaler Großkanzleien als auch die besonderen Anforderungen rund um hochwertige mobile Vermögenswerte. Mit den High Value Assets Roundtables bringt er Experten, Anbieter und Multiplikatoren verschiedener Asset-Klassen zusammen. Im Gespräch mit Markus Hill erläutert er seinen ungewöhnlichen Karriereweg, die Arbeit von Martyn Fiddler und warum ein gutes Netzwerk nicht vom Sammeln, sondern vom Teilen lebt.

Hill: Vom Geschichtsstudium über die Welt der Großkanzleien bis hin zu Business Jets und Yachten – ein Lebenslauf, den man sich kaum ausdenken könnte. Wer ist der Mensch dahinter und was macht ihn aus?

Tobias Heining, Martin Fiddler Aviation

Heining: Als ich 2001 meinen Masterabschluss in der Tasche hatte, begann ich bei einer PR-Agentur, die unter anderem große Rechtsanwaltskanzleien und Wirtschaftsprüfungsgesellschaften in Fragen der Öffentlichkeitsarbeit beriet. Das war damals noch ein relativ exotisches, aber spannendes und anspruchsvolles Tätigkeitsfeld. Von dort führte mich mein Weg auf die Kundenseite zu US-amerikanischen, britischen und deutschen Großkanzleien. Dort übernahm ich verschiedene Positionen bis hin zur Leitung großer Teams mit entsprechender Budgetverantwortung in den Bereichen Geschäftsentwicklung, Marketing und Kommunikation.

Von der Geschäftsentwicklung und strategischen Positionierung ist der gedankliche Weg zu Innovation, neuen Geschäftsmodellen sowie effizienteren Abläufen und Administrationsbereichen nicht weit. Als Führungskraft möchte ich Märkte, Strukturen und Prozesse verstehen und Dinge vorantreiben, um ein Unternehmen zukunftsfähig zu gestalten. In Zeiten künstlicher Intelligenz ist das wahrscheinlich eine der zentralen Herausforderungen. Genau das motiviert mich: Ich sehe mich als Strategen, Netzwerker und Innovator.

Bei aller Freude an Veränderung sind mir ein menschliches Verständnis und die Wahrung meiner persönlichen Integrität wichtig geblieben. Das mag auf den ersten Blick nicht immer vollständig vereinbar erscheinen. Der Wechsel in die Business Aviation und das Yachting kam auch für mich überraschend. Er hat sich jedoch als besonders erfrischende und bereichernde Erfahrung erwiesen. Die DNA dieser Branchen ist im Kern kooperativ und von einem hohen Maß an Pragmatismus und Offenheit geprägt. Das verlangt viel geistige Mobilität – und genau das gefällt mir.

Markus Hill, Finanzplatz Frankfurt & Tobias Heining, Martin Fiddler Aviation

Hill: Business Aviation und Yachting klingen spannend, aber auch ein wenig nebulös. Was genau macht das Unternehmen, für das Du tätig bist?

Heining: Nebulös ist in diesem Zusammenhang ein schönes Wort. Wir helfen unseren Kunden dabei, sicher durch einige Untiefen der Business Aviation und des Yachtings zu navigieren. Martyn Fiddler ist seit mehr als 40 Jahren eine Boutique für maßgeschneiderte internationale Lösungen – insbesondere für Eigentümer und Betreiber komplexer mobiler Vermögenswerte wie Business Jets, Helikopter und Yachten.

Im Kern ist Martyn Fiddler ein Corporate Service Provider, also Anbieter und Administrator von Zweckgesellschaften. Darüber hinaus bieten wir spezialisierte Steuerberatung und Unterstützung bei sämtlichen zollbezogenen Themen, beispielsweise beim Import und Export der Assets. Zudem pflegen wir ein weltweites Ökosystem enger Kooperationspartner und Kontakte. So können wir unseren Kunden auch bei praktischen Fragen jenseits unseres eigenen Leistungsportfolios Orientierung geben und geeignete professionelle Ansprechpartner vermitteln.

Markus Hill, Finanzplatz Frankfurt & Markus Schwingshackl, Centro LAW

Hill: Du hast Dir in unterschiedlichen Marktsegmenten den Ruf als Vordenker, Pionier und Netzwerker erworben – etwa im Rechtsmarkt durch die frühe Besetzung des Themas Legal Technology. Nun engagierst Du Dich im Bereich Business Jets und Yachten. Was treibt Dich zur Innovation, und wie entstand die Idee zu den High Value Assets Roundtables?

Heining: Ich glaube fest an die Kraft eines konstruktiven Austauschs und Erfahrungstransfers. Der Ausgangspunkt einer Netzwerkidee ist für mich deshalb immer ein Kommunikationsdefizit zwischen bestimmten Menschen oder Gruppen. Wenn dessen Überwindung gegenseitige Vorteile und Synergien verspricht, entsteht daraus eine echte Chance. So war es bei der Gründung der European Legal Technology Association, kurz ELTA, vor zehn Jahren – und so war es auch bei den High Value Assets Roundtables.

Der von mir 2014 initiierte Aufbau der ersten Legal-Tech-Abteilung einer deutschen Großkanzlei war für mich der Startschuss, über den deutschen Markt hinauszublicken. Doch wie so häufig in Europa wusste man in Deutschland nur wenig über die Entwicklungen in Frankreich, Spanien, Italien, den Niederlanden oder Mittel- und Osteuropa – und umgekehrt. In Großbritannien nahm man die Entwicklungen jenseits des Ärmelkanals ebenfalls nur eingeschränkt wahr. Mit der ELTA wollten wir die unterschiedlichen Innovatoren und Innovationszentren zusammenbringen und eine grenzüberschreitende Plattform für den Erfahrungsaustausch schaffen.

Als ich 2023 in die Business Aviation und das Yachting wechselte, stellte ich schnell fest: Obwohl sich die Zielgruppen stark überschneiden und die operativen sowie marktbezogenen Herausforderungen ähnlich sind, gab es keinen strukturierten Dialog zwischen den Vertretern verschiedener Asset-Klassen, Anbietern und Dienstleistern im Luxus-, Private-Clients- und UHNWI-Bereich. Auch in der DACH-Region fehlte eine entsprechende Plattform. Mit den High Value Assets Roundtables wollte ich diese Lücke schließen. Ich halte das für einen fruchtbaren Ansatz für alle Beteiligten.

Hill: Worum geht es konkret, und was macht das High Value Assets Netzwerk interessant?

Heining: Die Netzwerkplattform startete im vergangenen Jahr mit zwei Veranstaltungen im Mai und Oktober 2025 in Berlin. In diesem Jahr folgten bereits zwei weitere Events: im April in Deutschland und im Juni 2026 in Österreich. Unsere kommende Veranstaltung am 10. September in Zürich rundet die Roundtable-Aktivitäten in der DACH-Region für dieses Jahr ab.

Die Plattform soll den professionellen Austausch zwischen Vertretern verschiedener Asset-Klassen sowie Anbietern und Dienstleistern im Luxus-, Private-Clients- und UHNWI-Bereich ermöglichen und fördern. Wir alle leben von der Stärke, Breite und Tiefe unserer Netzwerke. Zugleich sind wir auf vertrauenswürdige Multiplikatoren mit Zugang zu den relevanten Zielgruppen angewiesen.

Bei den bisherigen High Value Assets Roundtables waren Gäste aus den Bereichen Business Aviation, Yachting, Immobilien, Automotive, Edelsteine und Edelmetalle, Wealth Management, Kunst und Kultur, Private Client Services, Finanzierung, Versicherung, Recht und Steuern sowie Sicherheitsarchitektur vertreten. Neben relevanten Zielgruppenthemen geht es immer wieder um die Besonderheiten und Marktspezifika der verschiedenen Asset-Klassen. Ebenso wichtig ist der Erfahrungsaustausch über vergleichbare operative Herausforderungen und mögliche Lösungsansätze. So erweitern wir zugleich unseren Horizont und unsere Netzwerkreichweite.

Hill: Wer gehört zum Teilnehmerkreis, und wie kann man teilnehmen?

Heining: Bei den verschiedenen Veranstaltungen konnten wir bislang bis zu 70 Gäste zusammenbringen. Das ist für ein Netzwerkformat eine gute Größenordnung. Wird die Gruppe größer, wird es schnell unübersichtlich – und ich möchte aus dem Format keine Konferenz machen. Der letzte High Value Assets Roundtable bei Wien war allerdings deutlich umfangreicher. Das lag an der hervorragenden Kooperation mit der Austrian Business Aviation Association, der ABAA.

Der Teilnehmerkreis besteht üblicherweise aus erfahrenen Vertretern verschiedener Asset-Klassen, Anbietern und Dienstleistern aus den genannten Segmenten. Bei der Auswahl stehen zwei Ebenen im Vordergrund. Fachlich zählen tiefgreifende berufliche Erfahrung und Expertise im Luxus-, Private-Clients- und UHNWI-Bereich, ein belastbares Netzwerk hochwertiger Kontakte sowie die Bereitschaft, Wissen und Kontakte im Interesse aller Beteiligten zu teilen.

Auf der menschlichen Seite geht es um Freude an neuen Ideen, den Blick über den fachlichen Tellerrand und die Bereitschaft, die eigene Erfahrung durch einen freundschaftlichen Austausch mit Gleichgesinnten zu erweitern. Das verlangt Offenheit, Authentizität, eine gewisse Bescheidenheit und eine positive Grundhaltung. Nachhaltigen Erfolg kann man in einem Netzwerk nur erzielen, wenn man bereit ist, selbst zu investieren und gelegentlich in Vorleistung zu gehen. Wer ausschließlich nehmen, aber nichts geben möchte, passt nicht in dieses Netzwerk. Das gilt wahrscheinlich auch für Menschen, die sich für etwas ganz Besonderes und Besseres halten.

Die Teilnahme erfolgt grundsätzlich auf persönliche Einladung durch mich. Eingeladene bitte ich um kurze Rücksprache, wenn sie eine andere Person entsenden oder weitere mögliche Teilnehmer vorschlagen möchten. So lässt sich sicherstellen, dass der Erfahrungsaustausch und die Qualität des Netzwerks auf einem konstant hohen Niveau bleiben.

Hill: Welche Pläne gibt es für die Zukunft des Netzwerks?

Heining: Teilnehmer aus der gesamten DACH-Region sind schon heute bei allen Veranstaltungen ausdrücklich willkommen und auch vertreten. Angesichts der Internationalität unserer Märkte und Zielgruppen möchte ich insbesondere die grenzüberschreitende Vernetzung dieser Kreise weiter stärken. Dazu gehört auch, das Netzwerk international auszubauen – beispielsweise nach London oder Monaco. Das steht zumindest für das kommende Jahr auf der Agenda.

Mein besonderer Fokus bleibt jedoch darauf, neue und spannende Menschen für das Netzwerk zu gewinnen und die Verbindungen in die einzelnen Asset-Klassen und Dienstleistungsbereiche weiter zu vertiefen. Mit einem stetig wachsenden Netzwerk wird man sich wahrscheinlich auch Gedanken über eine weitere Professionalisierung der Strukturen und gegebenenfalls über eine veränderte Aufgabenverteilung mit möglichen Kooperationspartnern machen müssen.

Hill: Vielen Dank für das Gespräch. Wir sind gespannt auf das Panel mit Markus Schwingshackl und wünschen viel Erfolg für den Abend in Zürich!

Impression & Philosophie, „Flavor“ des Abends in Zürich (Zitat – Tobias Heining):

„As part of our ongoing efforts to encourage meaningful networking among participants, I would be delighted if you could share one question about your business that you would most like fellow attendees to ask you. Rather than a general question such as ‚What exactly does your company do?‘ 😉, please consider something more insightful and specific. For example, it could relate to your unique value proposition, the business challenges you help solve, the market segments you serve, or even what really motivates you to go the extra mile or ways in which others could support your business growth.”

Panel-Diskussion (15:00 Uhr, 10.9.2026): Virtual Values – High Value Assets in the Digital Space

Teilnehmer:

  • Markus Schwingshakl ist Private Clients Anwalt und berät Unternehmer, Family Offices und Hochvermögende. Zudem ist er Mitbegründer des PKN Private Key Network, einem Netzwerk, das 2025 für Fachleute im Bereich Private Wealth/digitale Vermögenswerte und KI gegründet wurde und darauf abzielt, Industriestandards zu gestalten und die Zusammenarbeit unter Experten zu fördern.
  • Robin Kretzschmar ist Gründer von 7Assets. Das Team strebt danach, die Vermögensverwaltung durch den Einsatz künstlicher Intelligenz zu vereinfachen und zu verbessern und eine Plattform zu schaffen, die Privatanlegern, Finanzberatern und Institutionen gleichermaßen dient und letztlich hilft, eine Optimierung der Vermögensströme zu erzielen.
  • Hannes Gurzki ist anerkannter Experten für Luxusmarkenmanagement und -marketing mit Lehraufträgen an der International University of Monaco, ESSEC Business School und der Technischen Universität Braunschweig, der als Program Director an der ESMT Berlin auch mit weltweit führenden Unternehmen und Luxusmarken aus verschiedenen Sektoren an Wertschöpfungsstrategien arbeitet. Hannes hat bereits zum Thema „Luxusmarken im digitalen Raum“ im Harvard Business Review veröffentlicht. 
  • Marco Infuso, Head Digital Assets Sales Central Europe. Apex Group.

Moderator: Frank Liemandt ist Geschäftsführer des Deutschen Helikopter Verbandes und Organisator der European Rotors, der größten europäischen Helikoptermesse. Außerdem ist er Moderationsprofi und hat das Video-Interview-Format „Fly me to the top“ ins Leben gerufen.

LinkedIn-Profil von Tobias Heining:

Tobias Heining

Dialog & Information:

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – KANAL

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – GRUPPE

FONDSBOUTIQUEN auf LINKEDIN – KANAL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI-Region & FONDSBOUTIQUEN.DE (2026) – Themen, Interessen, Dialog (Auswahl & „Snapshots“)

25.2.2026, Frankfurt – „Finanzplatz Frankfurt am Main meets Wealthmanagement“

(Markus Hill – Moderation: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

26.2.2026, Frankfurt – „Forum für Digitale Vermögenswerte (FDV)“

Redaktion – Themenspecial „Finanzplatz Frankfurt am Main meets Wealthmanagement & Digital Assets“

(Interviews / Gastbeiträge, “Support” & MORE: info: markus-hill.com)

17.3.2026, Frankfurt – Private Markets Excellence Forum – „Private Markets, Family Offices & Stiftungen – Due Diligence & Ausblick 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Geschäftsführer, VIRATIO GmbH)

Interview mit Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Frühjahr 2026: Investorenstudie „Präferenzen institutioneller Investoren bei Immobilien & Alternative Investments“

(Markus Hill – Moderation, Podcast: Sebastian Thürmer, “artis & x” – Beispiel 2025)

16.4.2026 – „köln let’s talk“ – Bettina Timmler – Immobilien & Dialog

(Medienpartnerschaft)

12.5.2026, Frankfurt: „Value Investing & Rohstoffe & MORE“

(Markus Hill – Moderation & Kurzintro „Fondsboutiquen & USA-Formel“ – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANZPLATZ SCHWEIZ)

17.6.2026, Zürich: Insights – “Family Offices & Fondsboutiquen” – The Mountain Talks Summit – FUNDPLAT

(Vortrag – Markus Hill)

24.9.2026, Luzern: „Swiss Digital Finance Conference 2026“ – Markus Hill (PARTNER) spricht mit Jan Carlos Janke, Dozent im Themenfeld Digital Business & Innovation der Hochschule Luzern – Informatik

10.11.2026, Frankfurt: „Finanzplatz Frankfurt am Main meets Finanzplatz Liechtenstein“

(Markus Hill – Moderation – LAFV Liechtensteinischer Anlagefondsverband: Panel & Vorträge)

Input, Ideen & Anregungen zu den oben genannten Themen sind willkommen:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay & Finanzplatz Frankfurt

FINANZPLATZ FRANKFURT & FINANZPLATZ SCHWEIZ: Uetliberg, Frauen und Sicherheit – Technologie, Community, Stiftungen & Drinkschutzdeckel (INTERVIEW – Jacqueline Lehmann, CEO – P3ACH)

Der Finanzplatz Schweiz bringt eine Vielfalt von interessanten Personen in den Dialog. Auch dieses Jahr ergab sich bei dem THE FINANCE & FUTURE-Summit (Thomas Caduff)  am Uetliberg die Gelegenheit zum Kennenlernen von verschiedenen „Out-of-the-Box“-Themen, Frauen & Sicherheit. Wie kann ein persönliches Erlebnis den Blick auf dieses gesellschaftliche Problem grundlegend verändern? Bei Jacqueline Lehmann, CEO (P3ACH) war es die Belästigung durch einen Taxifahrer auf dem Weg zum Flughafen. Aus der eigenen Erfahrung entstand die Frage: Wie lässt sich Frauen im Alltag mehr Sicherheit geben – praktisch, digital und getragen von einer Gemeinschaft?

Im Gespräch mit Markus Hill & Mary Daute für FINANZPLATZ FRANKFURT erläutert Frau. Lehmann, CEO von  P3ACH warum Sicherheit nicht mit Angst kommuniziert werden sollte, welche Rolle die Community spielt und weshalb wirtschaftlicher Erfolg und soziale Wirkung zusammengehören.

Hill & Daute: Wir haben uns am 17. Juni 2026 beim „The Finance & Future“-Summit auf dem Uetliberg kennengelernt. Womit beschäftigen Sie sich derzeit intensiv?

Lehmann: Aktuell beschäftige ich mich sehr intensiv mit dem Thema Sicherheit im Alltag – insbesondere mit Frauensicherheit, Gewaltprävention und dem Schutz vor Übergriffen. Leider erleben wir, dass Frauen sich an vielen Orten zunehmend unsicher fühlen: auf dem Nachhauseweg, am Bahnhof, beim Ausgehen, beim Joggen oder ganz einfach im Alltag. Dabei sollte sich niemand in unserer Gesellschaft ständig Gedanken darüber machen müssen, ob der eigene Weg nach Hause sicher ist.

Hill & Daute: Das Thema Sicherheit von Frauen steht aktuell stark im Fokus bei Ihnen. Was war der Auslöser, sich intensiver damit auseinanderzusetzen?

Lehmann: Zum einen gab es ein persönliches Erlebnis: Ich wurde auf dem Weg zum Flughafen von einem Taxifahrer belästigt. Dieses Erlebnis hat mich dazu gebracht, mich intensiv mit dem Thema auseinanderzusetzen. Sehr schnell wurde mir bewusst, dass es sich nicht um Einzelfälle handelt. Belästigung, Übergriffe und Gewalt können Frauen an ganz unterschiedlichen Orten und in ganz unterschiedlichen Situationen begegnen. Daraus entstand der Wunsch, nicht nur über das Problem zu sprechen, sondern konkret etwas zu entwickeln, das Frauen mehr Sicherheit und ein stärkeres Gefühl von Selbstbestimmung gibt.

Hill & Daute: Welche besonderen Funktionen oder Ansätze bietet Ihr Unternehmen beziehungsweise Ihre App, um die Sicherheit von Frauen zu verbessern?

Mary Daute, Finanzplatz Frankfurt Am Main, Jacqueline Lehmann, CEO P3ACH – Uetliberg, Fundplat.com

Lehmann: Wir entwickeln derzeit eine App, die Frauen miteinander verbindet und einen sicheren Raum für Austausch, Unterstützung und Prävention schafft. Ein zentraler Gedanke ist, Frauen auf ihren Wegen begleiten zu können – beispielsweise auf dem Nachhauseweg oder beim Joggen. Wir möchten eine digitale Sicherheitsebene schaffen, die Frauen im Alltag unterstützt und ihnen ein Stück Sicherheit zurückgibt. Dabei setzen wir sehr stark auf Community. Gleichzeitig möchten wir sichere Fahrdienste integrieren und einen digitalen „Bodyguard“ entwickeln: eine intelligente Sicherheitsebene, die im Ernstfall unterstützen kann und zugleich von der Community mitgetragen wird. Unser Ziel ist es, Sicherheit nicht als etwas Bedrohliches oder Einschränkendes zu vermitteln, sondern als selbstverständlichen Bestandteil des modernen Alltags.

Hill & Daute: Welche anderen Maßnahmen werden derzeit ergriffen, um dieses Problem zu lösen? Wo kann Ihr Ansatz dazu beitragen, Frauen mehr Sicherheit zu geben?

Lehmann: Wir haben uns zunächst bewusst mit einer Lösung beschäftigt, die sofort eingesetzt werden kann – noch bevor unsere App vollständig verfügbar ist. Die App befindet sich aktuell in der Beta-Testphase. Bei der sofort einsetzbaren Lösung handelt es sich um unsere Drinkschutzdeckel, die insbesondere Frauen vor K.-o.-Tropfen schützen sollen. Sie bieten eine einfache Möglichkeit, das eigene Getränk beim Ausgehen besser zu schützen. Für uns ist das ein erster konkreter Schritt. Langfristig möchten wir mit P3ACH jedoch deutlich weiter gehen und verschiedene Sicherheitslösungen miteinander verbinden: physisch, digital und vor allem über eine starke Community.

Hill & Daute: Sie verbinden auch den Stiftungsgedanken mit Ihrer Kommunikation. Wie kam es zu dieser Idee?

Monika Kirse-Wenzel, Verein Geschäftsführerin

Lehmann: Der Gedanke war von Anfang an Teil von P3ACH. Wir wollten kein Unternehmen aufbauen, das ausschließlich kommerziell denkt, sondern eines, das zugleich eine echte gesellschaftliche Wirkung erzielt. Deshalb haben wir in diesem Jahr den P3ACH Verein gegründet, den Monika Kirse-Wenzel als Geschäftsführerin führt. So verbinden wir unser Sicherheitskonzept mit sozialem Engagement. Bei jedem verkauften Drinkschutzdeckel wird ein Teil des Erlöses an eine Brustkrebs-Stiftung in Deutschland gespendet. Damit möchten wir zeigen, dass wirtschaftlicher Erfolg und gesellschaftliche Verantwortung kein Widerspruch sein müssen. Für uns bedeutet P3ACH deshalb nicht nur Sicherheit, sondern auch Solidarität – und die Idee, gemeinsam etwas zu bewegen.

Hill & Daute: Was sind Ihre nächsten Aktivitäten in der DACH-Region?

Lehmann: Unser nächster Schritt ist der erste große Auftritt beim Abschlusskonzert der Hamburger Goldkehlchen im Volksparkstadion in Hamburg. Dort werden unsere Drinkschutzdeckel erhältlich sein. Gleichzeitig treten wir gemeinsam mit der Brustkrebs-Stiftung auf, um ihre wertvolle Arbeit sichtbar zu machen und Aufmerksamkeit für das Thema zu schaffen. Das ist für uns ein wichtiger nächster Schritt, weil wir P3ACH nicht nur als Produkt präsentieren möchten, sondern als Bewegung, die Sicherheit, Community und gesellschaftliches Engagement miteinander verbindet.

Hill & Daute: Vielen Dank für das Gespräch.

INFORMATION:

P3ach

Fundplat

Dialog & Information:

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – KANAL

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – GRUPPE

FONDSBOUTIQUEN auf LINKEDIN – KANAL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI-Region & FONDSBOUTIQUEN.DE (2026) – Themen, Interessen, Dialog (Auswahl & „Snapshots“)

25.2.2026, Frankfurt – „Finanzplatz Frankfurt am Main meets Wealthmanagement“

(Markus Hill – Moderation: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

26.2.2026, Frankfurt – „Forum für Digitale Vermögenswerte (FDV)“

Redaktion – Themenspecial „Finanzplatz Frankfurt am Main meets Wealthmanagement & Digital Assets“

(Interviews / Gastbeiträge, “Support” & MORE: info: markus-hill.com)

17.3.2026, Frankfurt – Private Markets Excellence Forum – „Private Markets, Family Offices & Stiftungen – Due Diligence & Ausblick 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Geschäftsführer, VIRATIO GmbH)

Interview mit Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Frühjahr 2026: Investorenstudie „Präferenzen institutioneller Investoren bei Immobilien & Alternative Investments“

(Markus Hill – Moderation, Podcast: Sebastian Thürmer, “artis & x” – Beispiel 2025)

16.4.2026 – „köln let’s talk“ – Bettina Timmler – Immobilien & Dialog

(Medienpartnerschaft)

12.5.2026, Frankfurt: „Value Investing & Rohstoffe & MORE“

(Markus Hill – Moderation & Kurzintro „Fondsboutiquen & USA-Formel“ – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANZPLATZ SCHWEIZ)

17.6.2026, Zürich: Insights – “Family Offices & Fondsboutiquen” – The Mountain Talks Summit – FUNDPLAT

(Vortrag – Markus Hill)

24.9.2026, Luzern: „Swiss Digital Finance Conference 2026“ – Markus Hill (PARTNER) spricht mit Jan Carlos Janke, Dozent im Themenfeld Digital Business & Innovation der Hochschule Luzern – Informatik

10.11.2026, Frankfurt: „Finanzplatz Frankfurt am Main meets Finanzplatz Liechtenstein“

(Markus Hill – Moderation – LAFV Liechtensteinischer Anlagefondsverband: Panel & Vorträge)

Input, Ideen & Anregungen zu den oben genannten Themen sind willkommen:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay & Finanzplatz Frankfurt

FRANKFURT AS A FINANCIAL CENTER & SWITZERLAND AS A FINANCIAL CENTER: Artificial Intelligence, Quantum Computing, Blockchain—Technology Convergence, Digital Sovereignty, and the Restructuring of  the Financial Architecture—September 24, 2026 (INTERVIEW—Jan Carlos Janke, Lucerne University of Applied Sciences and Arts)

Swiss Digital Finance Conference 2026, Digital Sovereignty Index, E-ID, and Digital Trust: Artificial intelligence, blockchain, digital identities, quantum computing, and new data infrastructures are often viewed as separate technological trends. In practice, however, these developments are increasingly beginning to converge.

This is precisely where the Swiss Digital Finance Conference 2026, hosted by Lucerne University of Applied Sciences and Arts on September 24, 2026, in Rotkreuz, comes in.

Under the theme “Technology Convergence – Redefining the Financial Architecture,” representatives from the financial sector, technology, academia, and the professional world will discuss what happens when individual innovations give rise to a new digital architecture.

But as technological interconnectivity increases, another question takes center stage:

To what extent do companies still retain sovereignty within these new digital structures?

This question leads directly to the next initiative from the Lucerne University of Applied Sciences and Arts: the Digital Sovereignty Index 2026, whose results will be presented on October 6, 2026, in Rotkreuz and discussed with representatives from business, technology, and academia.

Markus Hill discusses the connection between these topics with Jan Carlos Janke, a lecturer in the Digital Business & Innovation program at Lucerne University of Applied Sciences and Arts – Computer Science, project manager of the Swiss Digital Finance Conference, co-director of the Digital Sovereignty Index, and co-program director of the new CAS Digital Identity & Trust program.

Jan Carlos Janke, Hochschule Luzern

Hill: Mr. Janke, why do you think we need a Swiss Digital Finance Conference at all? There are already numerous banking, fintech, and technology conferences.Janke: That’s precisely why. Many events focus on individual aspects: AI, blockchain, digital assets, cybersecurity, fintech, or regulation. Our basic premise is different: The truly relevant changes are increasingly emerging at the intersections of these technologies. The financial industry isn’t simply experiencing another wave of digitization. We’re seeing a combination of artificial intelligence, highly automated processes, blockchain and distributed ledger infrastructures, digital identities, new forms of digital assets, and, looking ahead, quantum computing. The crucial question, therefore, is no longer just: Which technology will prevail? Rather: What happens when these technologies interact with one another and, through “ ,” enable new business models, processes, and market structures? This is precisely the perspective we aim to facilitate with the Swiss Digital Finance Conference.

Hill: Is that why the theme for 2026 is “Technology Convergence – Redefining the Financial Architecture”?

Janke: Exactly. We don’t want to discuss technology as an end in itself. AI, for example, can automate processes, analyze information, and prepare decisions. Blockchain and distributed ledger technologies can create new transaction and ownership structures. Digital identities and verifiable proofs, in turn, can clarify who or what is actually acting within digital processes and with what authorization. If, in the future, autonomous AI agents also trigger transactions or carry out business processes independently, these questions will become even more important. This quickly takes us from individual technologies to architecture: How do we design financial systems in which data, identities, assets, and automated actors can interact securely and trustworthily with one another?

Markus Hill, Finanzplatz Frankfurt am Main & Jan Carlos Janke, Hochschule Luzern

Hill: With Damir Bogdan, you’ve secured an expert in business transformation, AI, and quantum computing as a keynote speaker. What do you expect from his presentation?

Janke: His keynote, “Technology Convergence – AI, Quantum Computing, and the Race for Execution,” offers a perspective that’s important to us: Technological capabilities alone do not create a competitive advantage. What’s becoming increasingly crucial is the ability of organizations to meaningfully combine different technologies and translate them into scalable business models and processes. In my view, this also shifts the focus of management. It’s not enough to know which technologies might become relevant. Companies must be able to decide where to invest, which capabilities they want to control themselves, which ecosystems to leverage, and where dependencies are acceptable. And that brings us right to the topic of digital sovereignty.

Hill: Is that the connection to the Digital Sovereignty Index?

Janke: Yes—and that’s exactly why I don’t view the two events in isolation from one another. The Swiss Digital Finance Conference first asks: How is technological convergence changing the architecture of the financial system? A few days later, the Digital Sovereignty Index poses the follow-up question: How capable of acting and how self-determined are companies within this increasingly complex digital architecture? Together with our industry partner ti&m, the Lucerne University of Applied Sciences and Arts is using the Digital Sovereignty Index to examine how Swiss organizations assess digital sovereignty and what capabilities are necessary to achieve it. Among other things, this involves strategic and technological dependencies, data, infrastructure, governance, and the ability of organizations to shape their digital transformation in a self-determined manner. On October 6, 2026, we will present the results to the public for the first time and discuss them with experts from the fields of business, technology, and academia. Our goal is not to engage in an abstract debate about technological independence. Companies will continue to use international technology providers, cloud infrastructures, platforms, and specialized software in the future. The crucial question is rather: Where does an efficient division of labor give rise to a strategically problematic dependency—and does an organization still have sufficient options, expertise, and control to act autonomously?

Hill: What role do digital identities play in this context?

Janke: A very central one. We’re moving toward digital ecosystems where it’s no longer just people interacting with one another. Companies, government agencies, platforms, machines, and—increasingly—AI agents must all have roles, permissions, and credentials. Digital identity therefore means far more than just logging in or authenticating. With the Swiss e-ID, the swiyu Wallet, the federal government’s trust infrastructure, and verifiable credentials, an infrastructure is currently emerging that will make trustworthy digital interactions significantly easier and more automated. We are engaged with this development both in research and across various ecosystems, including within the context of DIDAS—theDigital Identity and Data Sovereignty Association—and the DIDAS Launchpad for the swiyu Ecosystem. The fundamental idea behind this is important: People and organizations should be able to use digital credentials reliably without having to exchange complete data sets with every interaction or rely on central platforms as the sole authority of trust. For me, this is a good example of how digital sovereignty does not mean isolating oneself technologically. On the contrary: sovereignty arises through choice, interoperability, and thoughtfully designed digital ecosystems.

Hill: You’re now incorporating these topics into continuing education programs at Lucerne University of Applied Sciences and Arts.

Janke: Yes. For me, this is exactly where the circle closes between research, practice, and continuing education. In the Digital Business & Innovation program at the Lucerne University of Applied Sciences and Arts, we explore how digital technologies are transforming business models, processes, and entire organizations—and how companies can actively shape this transformation. We deliberately focus on more than just individual technologies. We examine the interplay between technology, business models, innovation, organization, and digital ecosystems. A new component within this field is the CAS in Digital Identity & Trust, which I co-direct with Prof. Dr. Oliver Gilbert. Here, we examine digital identities, e-IDs, wallets, and verifiable credentials from more than just a technological perspective. Equally important are business models, governance, trust frameworks, interoperability, digital ecosystems, and digital sovereignty. After all, companies will need specialists and executives in the future who can bring these different perspectives together. Ultimately, this follows the same logic as the Swiss Digital Finance Conference: technology, business, and governance can be viewed less and less in isolation from one another.

Hill: Why is the financial sector particularly interesting in light of this development?

Janke: The financial industry is probably one of the sectors where this convergence is particularly evident. Banks already have complex identity, compliance, and transaction infrastructures in place. At the same time, new opportunities are emerging through AI, tokenization, digital assets, automated business processes, and digital credentials. Imagine, for example, a more highly automated financial process in which not only a customer’s identity is verified, but also their affiliation with a company, authority to act on behalf of the company, or regulatory documentation can be verified digitally and in a machine-readable format. If such documentation is available in an interoperable format, processes can be fundamentally reimagined. If we look ahead and combine this with AI agents, another dimension emerges. Then we must not only know who a person is, but also: On whose behalf is a digital agent acting? What powers does it have? And on what basis is it authorized to initiate a specific transaction? These are questions that touch on technology, governance, liability, regulation, cybersecurity, and trust all at once.

Hill: Frankfurt and Switzerland are two major financial and innovation hubs. Where do you see opportunities for greater collaboration?

Janke: Plenty. I worked in Frankfurt for several years myself and find the two ecosystems to be highly complementary. Frankfurt boasts an enormous concentration of banks, asset managers, regulatory bodies, infrastructure companies, and institutional investors. Switzerland, on the other hand, has a strong innovation ecosystem centered on fintech, blockchain, digital assets, digital identities, and new digital trust infrastructures. That’s why, especially when it comes to topics like tokenization, AI in the financial sector, digital identity, or digital sovereignty, it’s worthwhile to exchange ideas across national and ecosystem boundaries. Technological transformation doesn’t stop at national borders anyway. In my view, the Swiss Digital Finance Conference on September 24 offers an ideal platform for this.

Hill: What should participants take away from the Swiss Digital Finance Conference?

Janke: Ideally, not just a list of new technologies. I want them to recognize the connections. Which technologies are beginning to reinforce one another? What new business models are emerging from this? What infrastructure is needed for this? Where are new dependencies arising? And what capabilities does my organization need to build today so that it can still make autonomous decisions tomorrow? If, the next morning, someone in the company doesn’t ask: “Do we need AI, blockchain, or quantum computing now, too?” but instead: “How does the combination of these developments change our future architecture and our strategic options?” then we’ve achieved a great deal. And the discussion doesn’t end on September 24. On the contrary. I see the Swiss Digital Finance Conference on September 24 and the presentation of the Digital Sovereignty Index on October 6 as two stages of the same discussion. The first event focuses more on the technological future of financial architecture. The second provides a data-driven assessment of where we stand: How well are Swiss organizations prepared for precisely this future—and how sovereignly can they actually shape their digital transformation? In between lie topics such as e-ID, digital identities, verifiable credentials, swiyu, AI, the cloud, blockchain, and new digital ecosystems. It is precisely this connection between technology, business, and transformation that also defines the Digital Business & Innovation program at Lucerne University of Applied Sciences and Arts and the new CAS in Digital Identity & Trust. What ultimately ties all these topics together is a central management question: How do we leverage the opportunities of an increasingly interconnected digital world without losing control over our own ability to act? This is exactly what the financial sector, technology companies, academia, and policymakers should be discussing together right now.

About Jan Carlos Janke

Jan Carlos Janke is a lecturer in the Digital Business & Innovation program at Lucerne University of Applied Sciences and Arts – Computer Science.

He is the project manager of the Swiss Digital Finance Conference, co-director of the Digital Sovereignty Index 2026, and co-program director of the CAS Digital Identity & Trust program.

His work lies at the intersection of digital finance, technological innovation, digital identities, blockchain, digital assets, digital ecosystems, and digital sovereignty.

About Markus Hill (Swiss Digital Finance Conference 2026)

Markus Hill is an independent asset management consultant and has been active for many years as a specialist author, moderator, and interviewer at the intersection of asset management, the fund industry, and the financial sector.

Further Information

Swiss Digital Finance Conference 2026 – September 24, 2026

Swiss Digital Finance Conference

Digital Sovereignty Index – Presentation and Discussion on October 6, 2026

www.hslu.ch

HSLU Research Area: Digital Business & Innovation

www.hslu.ch.de-ch.informatik

Dialogue & Information:

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – CHANNEL

FRANKFURT AM MAIN FINANCIAL CENTER on LINKEDIN – GROUP

FUND BOUTIQUES on LINKEDIN – CHANNEL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI Region & FONDSBOUTIQUEN.DE (2026) – Topics, Interests, Dialogue (Selection & “Snapshots”)

February 25, 2026, Frankfurt – “Frankfurt am Main Financial Center Meets Wealth Management”

(Markus Hill – Moderators: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

February 26, 2026, Frankfurt – “Forum for Digital Assets (FDV)”

Editorial Team – Special Feature “Frankfurt am Main Financial Center Meets Wealth Management & Digital Assets”

(Interviews / Guest Contributions, “Support” & MORE: info: markus-hill.com)

March 17, 2026, Frankfurt – Private Markets Excellence Forum – “Private Markets, Family Offices & Foundations – Due Diligence & Outlook 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Managing Director, VIRATIO GmbH)

Interview with Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Spring 2026: Investor Study “Preferences of Institutional Investors in Real Estate & Alternative Investments”

(Markus Hill – Moderator, Podcast: Sebastian Thürmer, “artis & x” – Example 2025)

April 16, 2026 – “köln let’s talk” – Bettina Timmler – Real Estate & Dialogue

(Media Partnership)

May 12, 2026, Frankfurt: “Value Investing & Commodities & MORE”

(Markus Hill – Moderator & brief introduction “Fund Boutiques & the U.S. Formula” – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANCIAL CENTER SWITZERLAND)

June 17, 2026, Zurich: Insights – “Family Offices & Fund Boutiques” – The Mountain Talks Summit – FUNDPLAT

(Presentation – Markus Hill)

September 24, 2026, Lucerne: “Swiss Digital Finance Conference 2026” – Markus Hill (PARTNER) speaks with Jan Carlos Janke, lecturer in Digital Business & Innovation at Lucerne University of Applied Sciences and Arts – Computer Science

November 10, 2026, Frankfurt: “Frankfurt am Main Financial Center Meets Liechtenstein Financial Center”

(Markus Hill – Moderator – LAFV Liechtenstein Investment Fund Association: Panel & Presentations)

Input, ideas, and suggestions on the topics mentioned above are welcome:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay

FINANCIAL CENTER FRANKFURT & FINANCIAL CENTER LIECHTENSTEIN: “Independent wealth managers, family offices, banks, and specialized asset managers in particular benefit from this unique positioning of Liechtenstein as a fund center.” (INTERVIEW – David Gamper, LAFV Liechtenstein Investment Fund Association)

Published 

Liechtenstein’s fund industry is growing—Markus Hill spoke with David Gamper, Managing Director of the Liechtenstein Investment Fund Association (LAFV), on behalf of FINANZPLATZ FRANKFURT AM MAIN, about the specialization in private-label funds, the role of dialogue-oriented supervision, and the biggest obstacle to growth: international recognition. Other topics include the recent roadshow in London and the question of why the British market is particularly interesting for Liechtenstein in the long term. On November 10, 2026, the LAFV will continue the dialogue in Frankfurt.

Hill: How is the Liechtenstein fund industry performing this year?
Gamper: We can be very satisfied with the first half of the year. Assets under management have risen by about 9%. Slightly more than a third of this growth is attributable to net inflows, with the remainder coming from price and currency gains. The number of new fund launches is also above last year’s level. This came as quite a surprise to us, as many of our members were simultaneously heavily occupied with implementing AIFMD II. These regulatory adjustments tied up significant personnel and organizational resources. It is therefore all the more gratifying that the industry was nevertheless able to maintain its growth momentum.

David Gamper, LAFV Liechtensteinischer Anlagefondsverband

Hill: You were just on a roadshow in London—not for the first time. Do you sense a change in the UK now?
Gamper: Yes, we’re seeing a very encouraging trend. Until a few years ago, Liechtenstein as a fund domicile was virtually unknown in the UK . We therefore had to lay the groundwork first and build awareness of the location in the first place. We only began targeted market development a few years ago; relative to the size of the UK market, we’re still operating on a comparatively modest budget. This makes it all the more gratifying that our efforts are increasingly bearing fruit. The number of participants in our roadshows is growing with each event. We’re having significantly more in-depth discussions with asset managers and service providers and are receiving more concrete inquiries. This is now also reflected in a growing number of funds being established in Liechtenstein by British asset managers. The British market is one of the largest and most international fund and asset management markets in Europe. Awareness and trust do not develop overnight there. However, developments to date show that Liechtenstein—with its short decision-making processes, high regulatory standards, and access to the European single market—is attracting increasing interest. We are convinced that in the UK, we are only at the beginning and still have considerable growth potential.

Hill: Liechtenstein is considered an important location for private-label funds. What is its particular strength?
Gamper: In recent years, Liechtenstein has deliberately positioned itself as a center of excellence for private-label funds. While major fund domiciles such as Luxembourg or Ireland primarily cater to international asset managers with very large fund volumes and structure their operations around economies of scale, Liechtenstein focuses on a different market segment. Here, private-label funds are not a niche product, but rather the core of the fund market. That is why all stakeholders—fund managers, custodian banks, specialized service providers, and the financial market supervisory authority—share a common interest in continuously improving the framework conditions for fund initiators and designing efficient processes. Independent asset managers, family offices, banks, and specialized asset managers in particular benefit from this unique positioning of Liechtenstein as a fund center. They find contacts who understand their business model, short decision-making paths, and a regulatory environment that enables innovation while ensuring high quality and compliance standards. This specialization is a genuine competitive advantage: In Liechtenstein, fund initiators are not just one of many clients—they are the focus of attention. This enables close collaboration, customized solutions, and a high quality of service—factors that are crucial in the private-label business.

Markus Hill, FINANZPLATZ FRANKFURT AM MAIN

Hill: What role does the Financial Market Authority play in the location’s attractiveness?
Gamper: The Financial Market Authority is a key factor in our success. An attractive fund center requires high regulatory standards and legal certainty, but also a regulator that seeks dialogue with market participants and facilitates efficient processes. It is precisely this combination that sets Liechtenstein apart. A particular advantage is the close and direct communication. Every fund company has a personal point of contact at the Financial Market Authority. Regular communication is not only possible but expressly encouraged. This is particularly helpful when dealing with more complex fund structures or innovative asset classes: early dialogue clarifies regulatory issues and efficiently prepares the approval process. The division of roles remains clear throughout. The Financial Market Authority does not act in an advisory capacity, but sees itself as an accessible and dialogue-oriented authority. Verena Schlömer of the Financial Market Authority recently put this aptly before fund sponsors: “We are not advisors, but we are happy to consult with you.” This statement sums up the Liechtenstein approach very well: talking to one another early on, fostering mutual understanding, and finding solutions within the regulatory framework. Short decision-making paths, dedicated points of contact, and constructive dialogue provide planning certainty. This allows even challenging fund projects to be implemented efficiently. Many market participants particularly appreciate this distinction when comparing Liechtenstein to other international markets.

Hill: How does European regulation affect a small fund center like Liechtenstein?
Gamper: European regulation naturally has a noticeable impact on a small fund center. For small and medium-sized companies—which are typical here—implementing new requirements often entails considerable effort and additional resources. At the same time, Liechtenstein has an important advantage: The regulator implements European requirements in a targeted manner and—unlike some other fund centers—avoids imposing additional restrictions beyond those set by Brussels. This pragmatic approach strikes a balance between necessary regulation and competitiveness. Both local companies and fund sponsors benefit from this. They receive a reliable regulatory framework without unnecessary additional hurdles. For a small fund center, it is crucial to remain efficient while meeting high European standards.

Hill: What is currently the biggest obstacle to further growth?
Gamper: In our view, the biggest obstacle is not the quality of the location, but its visibility. Anyone who gets to know Liechtenstein as a fund location more closely is generally convinced by the framework conditions and the ecosystem’s capabilities. Many then wonder why growth isn’t even stronger—and usually reach the same conclusion: Liechtenstein’s strengths are still not well known internationally. Luxembourg and Ireland have been established as fund domiciles for decades and invest significant resources in their international marketing. Our association is working with a comparatively limited budget to gradually increase awareness—through roadshows, social media, and direct engagement with fund sponsors such as asset managers, wealth managers, and family offices. I am convinced that the more potential fund sponsors get to know Liechtenstein, the stronger the growth will be. Our task, therefore, is to further increase visibility and promote the location’s strengths even more effectively in international markets.

Hill: When will you be in Germany next?
Gamper: We’ll be in Frankfurt on November 10, 2026. Joining us will be the Deputy Ambassador in Berlin, H.E. Ulrich von Liechtenstein; Klaus Deng, Senior Partner at Brehmer & CIE. Family Office; Verena Schlömer from the Liechtenstein Financial Market Authority ( ); Florian Steiger, CEO and founder of Icosa Investments AG; Thomas Marte, President of the LAFV; and myself. Those interested can find more information and register on our website.

Hill: Thank you very much for the interview.

Frankfurt as a Financial Center Meets Liechtenstein as a Fund Center” – Event Announcement & Registration:

Information and Registration

Dialogue & Information:

FINANZPLATZ FRANKFURT AM MAIN on LINKEDIN – CHANNEL

FRANKFURT AM MAIN FINANCIAL CENTER on LINKEDIN – GROUP

FUND BOUTIQUES on LINKEDIN – CHANNEL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI Region & FONDSBOUTIQUEN.DE (2026) – Topics, Interests, Dialogue (Selection & “Snapshots”)

February 25, 2026, Frankfurt – “Frankfurt am Main Financial Center Meets Wealth Management”

(Markus Hill – Moderators: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

February 26, 2026, Frankfurt – “Forum for Digital Assets (FDV)”

Editorial Team – Special Feature “Frankfurt am Main Financial Center Meets Wealth Management & Digital Assets”

(Interviews / Guest Contributions, “Support” & MORE: info: markus-hill.com)

March 17, 2026, Frankfurt – Private Markets Excellence Forum – “Private Markets, Family Offices & Foundations – Due Diligence & Outlook 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Managing Director, VIRATIO GmbH)

Interview with Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Spring 2026: Investor Study “Preferences of Institutional Investors in Real Estate & Alternative Investments”

(Markus Hill – Moderator, Podcast: Sebastian Thürmer, “artis & x” – Example 2025)

April 16, 2026 – “köln let’s talk” – Bettina Timmler – Real Estate & Dialogue

(Media Partnership)

May 12, 2026, Frankfurt: “Value Investing & Commodities & MORE”

(Markus Hill – Moderator & brief introduction “Fund Boutiques & the U.S. Formula” – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANCIAL CENTER SWITZERLAND)

June 17, 2026, Zurich: Insights – “Family Offices & Fund Boutiques” – The Mountain Talks Summit – FUNDPLAT

(Presentation – Markus Hill)

September 24, 2026, Lucerne: “Swiss Digital Finance Conference 2026” – Markus Hill (PARTNER) speaks with Jan Carlos Janke, lecturer in Digital Business & Innovation at Lucerne University of Applied Sciences and Arts – Computer Science

November 10, 2026, Frankfurt: “Frankfurt am Main Financial Center Meets Liechtenstein Financial Center”

(Markus Hill – Moderator – LAFV Liechtenstein Investment Fund Association: Panel & Presentations)

Input, ideas, and suggestions on the topics mentioned above are welcome:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay

Source: IPE D.A.CH

FINANZPLATZ FRANKFURT & FINANZPLATZ LIECHTENSTEIN: „Gerade unabhängige Vermögensverwalter, Family Offices, Banken und spezialisierte Asset Manager profitieren von dieser besonderen Positionierung des Fondsplatzes Liechtenstein“ (INTERVIEW – David Gamper, LAFV Liechtensteinischer Anlagefondsverband)

Der Fondsplatz Liechtenstein wächst – Markus Hill sprach für FINANZPLATZ FRANKFURT AM MAIN mit David Gamper, Geschäftsführer des Liechtensteinischen Anlagefondsverbands (LAFV), über die Spezialisierung auf Private-Label-Fonds, die Rolle einer dialogorientierten Aufsicht und die noch immer größte Wachstumsbremse: die internationale Bekanntheit. Weitere Themen sind die jüngste Roadshow in London und die Frage, weshalb der britische Markt für Liechtenstein langfristig besonders interessant ist. Am 10. November 2026 setzt der LAFV den Dialog in Frankfurt fort.

Hill: Wie entwickelt sich die liechtensteinische Fondsbranche in diesem Jahr?
Gamper: Wir können mit dem ersten Halbjahr sehr zufrieden sein. Die Assets under Management sind um rund 9% gestiegen. Etwas mehr als ein Drittel dieses Wachstums ist auf Nettomittelzuflüsse zurückzuführen, der übrige Anstieg auf Kurs- und Währungsgewinne. Auch die Zahl der Fondsneugründungen liegt über dem Vorjahresniveau. Das hat uns durchaus überrascht, denn viele unserer Mitglieder waren gleichzeitig stark mit der Umsetzung der AIFMD II beschäftigt. Diese regulatorischen Anpassungen haben erhebliche personelle und organisatorische Ressourcen gebunden. Umso erfreulicher ist es, dass die Branche ihre Wachstumsdynamik dennoch beibehalten konnte.

David Gamper, LAFV Liechtensteinischer Anlagefondsverband

Hill: Sie waren gerade auf Roadshow in London – nicht zum ersten Mal. Spüren Sie in Großbritannien inzwischen eine Veränderung?
Gamper: Ja, wir sehen eine sehr erfreuliche Entwicklung. Das Fondsdomizil Liechtenstein war in Großbritannien bis vor wenigen Jahren praktisch unbekannt. Wir mussten daher zunächst Grundlagenarbeit leisten und überhaupt ein Bewusstsein für den Standort schaffen. Die gezielte Marktbearbeitung haben wir erst vor wenigen Jahren aufgenommen; gemessen an der Größe des britischen Marktes arbeiten wir nach wie vor mit einem vergleichsweise bescheidenen Budget. Umso erfreulicher ist es, dass unsere Aktivitäten zunehmend Früchte tragen. Die Zahl der Teilnehmenden an unseren Roadshows wächst von Veranstaltung zu Veranstaltung. Wir führen deutlich mehr vertiefte Gespräche mit Asset Managern und Dienstleistern und verzeichnen mehr konkrete Anfragen. Inzwischen zeigt sich das auch in einer wachsenden Zahl von Fondsgründungen britischer Asset Manager in Liechtenstein. Der britische Markt gehört zu den größten und internationalsten Fonds- und Asset-Management-Märkten Europas. Bekanntheit und Vertrauen entstehen dort nicht über Nacht. Die bisherige Entwicklung zeigt jedoch, dass Liechtenstein mit kurzen Entscheidungswegen, hoher regulatorischer Qualität und Zugang zum europäischen Binnenmarkt auf ein zunehmendes Interesse stößt. Wir sind überzeugt: In Großbritannien stehen wir erst am Anfang und verfügen noch über erhebliches Wachstumspotenzial.

Hill: Liechtenstein gilt als wichtiger Standort für Private-Label-Fonds. Worin liegt die besondere Stärke?
Gamper: Liechtenstein hat sich in den vergangenen Jahren ganz bewusst als Kompetenzzentrum für Private-Label-Fonds positioniert. Während große Fondsdomizile wie Luxemburg oder Irland vor allem internationale Asset Manager mit sehr hohen Fondsvolumina adressieren und ihre Strukturen auf Skaleneffekte ausrichten, konzentriert sich Liechtenstein auf ein anderes Marktsegment. Private-Label-Fonds sind bei uns kein Nischenprodukt, sondern der Kern des Fondsmarktes. Deshalb haben alle Beteiligten – Fondsleitungen, Depotbanken, spezialisierte Dienstleister und Finanzmarktaufsicht – ein gemeinsames Interesse daran, die Rahmenbedingungen für Fondsinitiatoren kontinuierlich zu verbessern und Prozesse effizient zu gestalten. Gerade unabhängige Vermögensverwalter, Family Offices, Banken und spezialisierte Asset Manager profitieren von dieser besonderen Positionierung des Fondsplatzes Liechtenstein. Sie finden Ansprechpartner, die ihr Geschäftsmodell verstehen, kurze Entscheidungswege sowie ein regulatorisches Umfeld, das Innovation ermöglicht und zugleich hohe Qualitäts- und Compliance-Standards gewährleistet. Diese Spezialisierung ist ein echter Wettbewerbsvorteil: Fondsinitiatoren sind in Liechtenstein nicht einer von vielen Kunden, sondern stehen im Mittelpunkt. Das ermöglicht eine enge Zusammenarbeit, individuelle Lösungen und eine hohe Servicequalität – Faktoren, die im Private-Label-Geschäft entscheidend sind.

Hill: Welche Rolle spielt die Finanzmarktaufsicht für die Attraktivität des Standorts?
Gamper: Die Finanzmarktaufsicht ist ein wesentlicher Erfolgsfaktor. Ein attraktiver Fondsplatz braucht hohe regulatorische Standards und Rechtssicherheit, aber ebenso eine Aufsicht, die den Dialog mit den Marktteilnehmern sucht und effiziente Prozesse ermöglicht. Genau diese Kombination zeichnet Liechtenstein aus. Ein besonderer Vorteil ist die enge und direkte Kommunikation. Jede Fondsgesellschaft verfügt über einen persönlichen Ansprechpartner bei der Finanzmarktaufsicht. Der regelmäßige Austausch ist nicht nur möglich, sondern ausdrücklich erwünscht. Das ist vor allem bei komplexeren Fondsstrukturen oder innovativen Anlageklassen hilfreich: Ein frühzeitiger Dialog klärt regulatorische Fragen und bereitet den Bewilligungsprozess effizient vor. Die Rollenverteilung bleibt dabei klar. Die Finanzmarktaufsicht übernimmt keine Beratungsfunktion, versteht sich aber als zugängliche und dialogorientierte Behörde. Verena Schlömer von der Finanzmarktaufsicht hat dies kürzlich vor Fondsinitiatoren treffend formuliert: «Wir sind keine Berater, beraten aber gerne mit Ihnen.» Dieser Satz bringt den liechtensteinischen Ansatz sehr gut auf den Punkt: frühzeitig miteinander sprechen, gegenseitiges Verständnis schaffen und Lösungen innerhalb des regulatorischen Rahmens finden. Kurze Wege, feste Ansprechpartner und ein konstruktiver Austausch schaffen Planungssicherheit. So lassen sich auch anspruchsvolle Fondsprojekte effizient umsetzen. Diesen Unterschied schätzen viele Marktteilnehmer im internationalen Vergleich besonders.

Hill: Wie wirkt sich die europäische Regulierung auf einen kleinen Fondsstandort wie Liechtenstein aus?
Gamper: Die europäische Regulierung hat für einen kleinen Fondsstandort natürlich spürbare Auswirkungen. Für kleine und mittelgroße Unternehmen, wie sie hierzulande typisch sind, bedeutet die Umsetzung neuer Anforderungen häufig erheblichen Aufwand und zusätzliche Ressourcen. Gleichzeitig besitzt Liechtenstein einen wichtigen Vorteil: Der Regulator setzt die europäischen Vorgaben zielgerichtet um und vermeidet – anders als manche andere Fondsstandorte – zusätzliche Verschärfungen über die Brüsseler Vorgaben hinaus. Diese pragmatische Herangehensweise schafft ein ausgewogenes Verhältnis zwischen notwendiger Regulierung und Wettbewerbsfähigkeit. Davon profitieren die ansässigen Unternehmen ebenso wie die Fondsinitiatoren. Sie erhalten einen verlässlichen regulatorischen Rahmen, ohne unnötige zusätzliche Hürden. Für einen kleinen Fondsstandort ist es entscheidend, effizient zu bleiben und gleichzeitig die hohen europäischen Standards zu erfüllen.

Markus Hill, FINANZPLATZ FRANKFURT AM MAIN

Hill: Was ist derzeit das größte Hemmnis für weiteres Wachstum?
Gamper: Das größte Hemmnis ist aus unserer Sicht nicht die Qualität des Standorts, sondern seine Bekanntheit. Wer den Fondsstandort Liechtenstein näher kennenlernt, ist in der Regel von den Rahmenbedingungen und der Leistungsfähigkeit des Ökosystems überzeugt. Viele fragen sich dann, weshalb das Wachstum nicht noch stärker ausfällt – und gelangen meist zum gleichen Schluss: Die Stärken Liechtensteins sind international noch immer zu wenig bekannt. Luxemburg und Irland sind seit Jahrzehnten als Fondsdomizile etabliert und investieren erhebliche Mittel in ihre internationale Vermarktung. Unser Verband arbeitet mit einem vergleichsweise begrenzten Budget daran, die Bekanntheit Schritt für Schritt zu erhöhen – mit Roadshows, Social Media und dem direkten Austausch mit Fondsinitiatoren wie Asset Managern, Vermögensverwaltern und Family Offices. Ich bin überzeugt: Je mehr potenzielle Fondsinitiatoren Liechtenstein kennenlernen, desto stärker wird das Wachstum ausfallen. Unsere Aufgabe besteht daher darin, die Sichtbarkeit weiter zu erhöhen und die Stärken des Standorts noch gezielter in die internationalen Märkte zu tragen.

Hill: Wann sind Sie das nächste Mal in Deutschland?
Gamper: Wir werden am 10. November 2026 in Frankfurt sein. Mit dabei sind der stellvertretende Botschafter in Berlin, S.D. Ulrich von Liechtenstein, Klaus Deng, Senior Partner bei Brehmer & CIE. Family Office, Verena Schlömer von der Finanzmarktaufsicht Liechtenstein, Florian Steiger, CEO und Gründer der Icosa Investments AG, Thomas Marte, Präsident des LAFV, und ich selbst. Nähere Informationen und die Möglichkeit zur Anmeldung finden Interessierte auf unserer Website.

Hill: Vielen Dank für das Gespräch.

Finanzplatz Frankfurt trifft Fondsplatz Liechtenstein“ – Veranstaltungshinweis & Anmeldung:

Informationen und Anmeldung

Dialog & Information:

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – KANAL

FINANZPLATZ FRANKFURT AM MAIN auf LINKEDIN – GRUPPE

FONDSBOUTIQUEN auf LINKEDIN – KANAL

FINANZPLATZ-FRANKFURT-MAIN.DE, DACHLI-Region & FONDSBOUTIQUEN.DE (2026) – Themen, Interessen, Dialog (Auswahl & „Snapshots“)

25.2.2026, Frankfurt – „Finanzplatz Frankfurt am Main meets Wealthmanagement“

(Markus Hill – Moderation: Christian Neuhaus – FINVIA, Sven Karkossa – Capitell Vermögens-Management AG, Noel Zeh – Wunderland Capital)

26.2.2026, Frankfurt – „Forum für Digitale Vermögenswerte (FDV)“

Redaktion – Themenspecial „Finanzplatz Frankfurt am Main meets Wealthmanagement & Digital Assets“

(Interviews / Gastbeiträge, “Support” & MORE: info: markus-hill.com)

17.3.2026, Frankfurt – Private Markets Excellence Forum – „Private Markets, Family Offices & Stiftungen – Due Diligence & Ausblick 2026”

(Markus Hill – Fireside Chat: J. Paulo Dos Santos – Geschäftsführer, VIRATIO GmbH)

Interview mit Christian Hommens – SMART IMPACT INVESTING & PRIVATE MARKETS

Frühjahr 2026: Investorenstudie „Präferenzen institutioneller Investoren bei Immobilien & Alternative Investments“

(Markus Hill – Moderation, Podcast: Sebastian Thürmer, “artis & x” – Beispiel 2025)

16.4.2026 – „köln let’s talk“ – Bettina Timmler – Immobilien & Dialog

(Medienpartnerschaft)

12.5.2026, Frankfurt: „Value Investing & Rohstoffe & MORE“

(Markus Hill – Moderation & Kurzintro „Fondsboutiquen & USA-Formel“ – Alex J. Rauschenstein & Urs Marti, SIA FUNDS AG – FINANZPLATZ SCHWEIZ)

17.6.2026, Zürich: Insights – “Family Offices & Fondsboutiquen” – The Mountain Talks Summit – FUNDPLAT

(Vortrag – Markus Hill)

24.9.2026, Luzern: „Swiss Digital Finance Conference 2026“ – Markus Hill (PARTNER) spricht mit Jan Carlos Janke, Dozent im Themenfeld Digital Business & Innovation der Hochschule Luzern – Informatik

10.11.2026, Frankfurt: „Finanzplatz Frankfurt am Main meets Finanzplatz Liechtenstein“

(Markus Hill – Moderation – LAFV Liechtensteinischer Anlagefondsverband: Panel & Vorträge)

Input, Ideen & Anregungen zu den oben genannten Themen sind willkommen:

info@markus-hill.com / +49 (0) 163 4616 179

Photo: Pixabay

Quelle: IPE D.A.CH